A business personal property tax audit examines whether a company accurately reported the taxable assets, classifications and values associated with its business personal property. For CFOs, tax directors, controllers and organizations with large or complex asset portfolios, an audit can require more than producing a fixed asset list. The taxing authority may compare prior filings with accounting records, review asset locations and classifications, evaluate valuation assumptions and ask for documentation supporting changes from one reporting period to another.
Understanding what happens during a business personal property tax audit helps a business prepare its records, respond consistently and identify potential issues before determining how to respond to audit findings.
The exact procedures, deadlines, lookback periods and appeal rights vary by state and local jurisdiction. However, most BPP audits follow a similar progression from the initial audit notice through document review, reconciliation, valuation analysis and final findings.
What Is a Business Personal Property Tax Audit?
A business personal property tax audit is a review by a taxing authority to determine whether a business properly reported and valued taxable assets under the applicable jurisdiction’s rules.
Business personal property may include machinery, equipment, furniture, computers, medical equipment and other tangible assets used in business operations. Definitions, exemptions and reporting requirements vary by jurisdiction. Organizations that need broader support with filings, renditions, valuations and portfolio management can learn more about PVS’s business personal property tax services.
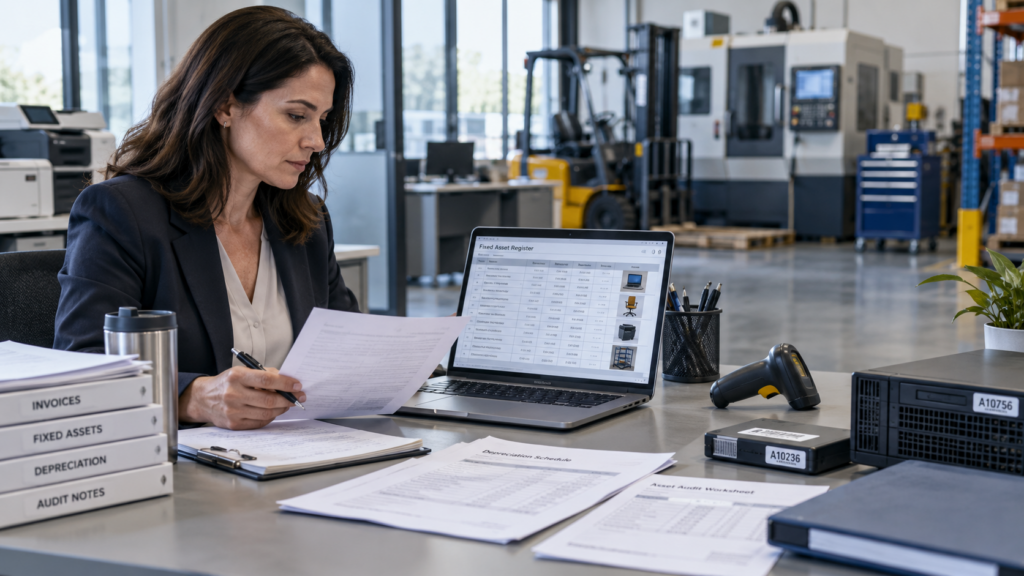
During an audit, the taxing authority may compare property tax filings with fixed asset records, depreciation schedules, acquisition and disposal information and other accounting documentation to determine whether the reported property and value are supportable.
The International Association of Assessing Officers (IAAO) notes in its Standard on Valuation of Personal Property that personal property audit programs may include reviewing depreciation schedules, ledger listings and fixed asset records and reconciling those records when they do not balance. IAAO standards are advisory, and applicable state and local laws and procedures govern each audit.
What Happens During a Business Personal Property Tax Audit?

During a business personal property tax audit, the taxing authority typically defines the scope of its review, requests supporting records, compares those records with prior property tax filings and investigates differences involving assets, locations, classifications or values. The process may include follow-up questions before the auditor issues findings or proposed adjustments.
Although procedures vary by jurisdiction, the process commonly includes seven stages.
1. The Business Receives an Audit Notice
The audit usually begins with written notice or another formal communication identifying what the taxing authority intends to review.
Before producing records, the business should understand the request’s scope.
Review:
- The legal entity or entities involved
- Property tax accounts or locations under review
- Tax years included
- Response deadlines
- Requested records
- The taxing authority’s contact information
- Any procedural information included with the notice
This is particularly important for multi-location and multi-state organizations. An audit involving one account or facility should be evaluated based on the scope identified by the jurisdiction rather than automatically treated as a portfolio-wide review.
2. The Business Reviews Its Property Tax and Asset Records
The next stage of property tax audit preparation is understanding how prior filings relate to the company’s underlying records.
Businesses may need to compare:
- Prior BPP returns or renditions
- Fixed asset ledgers
- Depreciation schedules
- General ledger accounts
- Acquisition information
- Disposal and retirement records
- Asset transfer records
- Lease schedules
The purpose is not simply to gather documents. It is to determine whether the company’s records tell a consistent story.
For example, equipment may have been physically retired but remain on an accounting ledger. An asset may also have moved between facilities while its cost center or accounting location remained unchanged.
Those differences require explanation and documentation, not assumptions.
3. The Auditor Reviews Supporting Documentation
The auditor may request records that help verify what property existed, where it was located, how it was reported and how the taxable value was determined.
Common records include:
Record
What It May Help Verify
Fixed asset ledger
Assets, costs, acquisition dates and recorded locations
Depreciation schedule
Historical costs and accounting treatment
General ledger
Completeness and reconciliation of asset accounts
Purchase invoices
Asset description and acquisition information
Disposal records
Whether property was sold, retired or scrapped
Transfer records
Movement between facilities or jurisdictions
Lease schedules
Ownership and potential reporting responsibility
Prior BPP filings
What was reported during the periods under review
The exact documentation required depends on the jurisdiction and the issues identified during the audit.
Businesses should understand what each request is intended to verify and organize the response accordingly rather than submitting large volumes of records without context.
4. The Auditor Reconciles Prior Filings With Company Records
Once supporting records are available, the auditor may compare the company’s property tax filings with its accounting information.
Potential differences may include:
- Assets in the accounting records that do not appear on the BPP return
- Property listed in more than one location
- Disposed assets that remain on a filing
- Differences between accounting cost and reported cost
- Equipment transfers not reflected in location-specific filings
- Significant changes in reported value from one year to another
A difference does not automatically mean the property tax filing was incorrect.
Accounting records and property tax records serve different purposes. A fixed asset ledger may include property that is exempt, located in another jurisdiction, leased or no longer physically present.
The audit response should explain the facts behind the difference and provide documentation where appropriate.
5. The Auditor Reviews Asset Classification and BPP Valuation
A BPP audit may also examine whether property was classified and valued appropriately.
The review can involve factors such as:
- Original or historical cost
- Acquisition year
- Asset category
- Physical location
- Estimated economic life
- Depreciation treatment
- Functional characteristics
- Applicable jurisdictional valuation methodology
Classification matters because different asset types may have different economic lives and valuation characteristics.
For example, high-technology medical equipment, manufacturing machinery, computer servers and office furniture should not automatically be viewed as economically identical simply because each appears on a company’s fixed asset schedule.
Property tax valuation methodology also differs from financial accounting depreciation. Taxing authorities may use cost schedules, depreciation factors and other approaches established by the applicable jurisdiction. Businesses that want additional context on this part of the process can review how assessors evaluate business personal property.
This is why BPP valuation can become a substantive part of an audit rather than a simple review of book depreciation.
6. The Business Responds to Follow-Up Questions
Audits often involve additional questions after the auditor reviews the initial records.
An auditor may ask why:
- Assets disappeared between reporting periods
- Costs differ between tax filings and accounting records
- Reported value changed significantly
- Equipment moved between locations
- Certain assets were treated differently from others
- A particular valuation or classification approach was used
Responses should address the specific question, connect the explanation to available documentation and remain consistent with the business’s broader audit position.
Organized responses are particularly important when several departments are involved. Tax, accounting, finance, operations and asset-management teams may each hold different pieces of the information needed to explain an asset’s history.
7. The Business Reviews the Audit Findings
After completing its review, the taxing authority may issue preliminary or final findings.
The result may involve:
- No material adjustment
- Corrections to asset information
- Classification changes
- Changes to taxable value
- Additional assessments
- Adjustments involving earlier reporting periods
Review the findings carefully against the underlying records and valuation assumptions.
The business should determine whether the proposed changes match the records, whether the valuation assumptions are supportable and whether relevant information was overlooked.
If the business disagrees with the findings, the available next steps depend on the jurisdiction. Those options may include providing additional documentation, requesting a correction or administrative review, discussing disputed items with the taxing authority or pursuing a formal challenge.
PVS’s guide to the business personal property tax protest process explains how a protest may come into play when a business believes an assessment is inaccurate.
What Should a Business Do During a BPP Audit?
A disciplined audit response focuses on accuracy, documentation and consistency.
Confirm the Scope Before Responding
Understand the accounts, locations, periods and records included in the audit before producing information.
Reconcile Records Before Submission
Compare property tax filings with the fixed asset ledger and other supporting records. Identify differences involving acquisitions, disposals, transfers or classifications so they can be explained.
Document Asset Changes
Do not rely solely on an asset’s current accounting status. Where relevant, maintain support showing when property was acquired, relocated, disposed of or removed from service.
Review Valuation Assumptions
Determine whether asset categories, economic lives and other valuation inputs appropriately reflect the property under review.
Track Questions and Responses
Maintain a clear record of requests, documents provided and explanations submitted. This becomes increasingly important during complex or multi-year audits.
The objective is not to produce the largest possible response. It is to provide organized information that supports an accurate property tax position.
Why Are Some BPP Audits More Complex?

Audit complexity often increases with the size, specialization and geographic distribution of a company’s asset portfolio.
Healthcare
Hospitals, surgery centers, imaging facilities and other healthcare organizations may manage large inventories of specialized medical technology with different acquisition dates, economic lives and replacement cycles.
Rapid technological change can also make valuation analysis more important for certain equipment categories.
Industrial and Manufacturing
Industrial operators may have production machinery, tooling, automated systems, spare equipment and assets that are modified or moved between facilities.
Determining what remained in service, where an asset was located and how equipment should be classified can require input from operations in addition to accounting records.
Multi-Location Organizations
Companies operating across multiple jurisdictions may maintain one centralized asset system while filing numerous local BPP returns.
Asset transfers, acquisitions, closures and accounting-system changes can create differences between the central asset database and location-specific property tax filings.
Because property tax rules vary by jurisdiction, these organizations must also account for different filing requirements, assessment practices and response procedures.
When Can a BPP Audit Require Additional Review?
Some BPP audits require additional review because the records or valuation questions are more complex than a straightforward reconciliation.
Additional review may be useful when:
- Fixed asset records do not reconcile with prior BPP filings
- Specialized or high-value equipment requires closer classification or valuation analysis
- Assets have moved among multiple locations or jurisdictions
- Acquisition, disposal or retirement records are incomplete
- Significant differences exist between accounting records and reported property
- Proposed adjustments depend on assumptions that need to be evaluated against supporting records
In these situations, the focus remains on understanding the records, resolving differences and determining whether the audit findings accurately reflect the property under review.
PVS assists businesses with complex BPP audit reviews involving asset records, valuation questions and supporting documentation. More information is available through PVS’s property tax audit services.
Frequently Asked Questions
How Long Does a Business Personal Property Tax Audit Take?
There is no universal timeline. The duration depends on the jurisdiction, the number of accounts and years under review, the complexity of the asset portfolio, the condition of the records, and the amount of follow-up required.
Businesses should rely on the deadlines and procedural information applicable to the specific audit.
Can a BPP Audit Identify Assessment or Reporting Errors?
Yes, depending on the facts and applicable jurisdictional procedures. Reconciliation may identify retired assets, omitted property, duplicate records, incorrect location information, classification issues or other discrepancies that affect the accuracy of a filing or assessment.
Whether an existing assessment or filing can be corrected depends on local rules, procedures and deadlines.
What Happens if a Business Disagrees With the Audit Findings?
A business may be able to provide additional records, request a correction or review, discuss disputed findings with the taxing authority or pursue a formal property tax protest or appeal.
Available procedures and deadlines vary by jurisdiction, so evaluate findings promptly.
Is Accounting Depreciation the Same as BPP Valuation?
No. Financial accounting depreciation and property tax valuation serve different purposes.
A taxing authority may use cost schedules, depreciation factors or other valuation methodologies established under state or local rules. The appropriate treatment depends on the property and jurisdiction.
How Far Back Can a Business Personal Property Tax Audit Review Records?
No single national lookback period exists. The years subject to review depend on applicable state law, local procedures and the circumstances of the audit.
Businesses should confirm the periods identified in the audit notice and review jurisdiction-specific requirements before deciding which records to produce.
Request a Property Tax Audit Review
A business personal property tax audit requires more than gathering accounting files. Businesses need to understand what was reported, reconcile differences, support asset changes and evaluate whether classification and valuation assumptions accurately reflect the property under review.
PVS helps organizations with complex, multi-location and equipment-heavy portfolios review BPP audit records, valuation questions and supporting documentation.
Request a Property Tax Audit Review
External Source: International Association of Assessing Officers, Standard on Valuation of Personal Property