Blog

What Happens During a Business Personal Property Tax Audit?

What Happens During a Business Personal Property Tax Audit?

A business personal property tax audit examines whether a company accurately reported the taxable assets, classifications and values associated with its business personal property. For CFOs, tax directors, controllers and organizations with large or complex asset portfolios, an audit can require more than producing a fixed asset list. The taxing authority may compare prior filings with accounting records, review asset locations and classifications, evaluate valuation assumptions and ask for documentation supporting changes from one reporting period to another.

Understanding what happens during a business personal property tax audit helps a business prepare its records, respond consistently and identify potential issues before determining how to respond to audit findings.

The exact procedures, deadlines, lookback periods and appeal rights vary by state and local jurisdiction. However, most BPP audits follow a similar progression from the initial audit notice through document review, reconciliation, valuation analysis and final findings.

What Is a Business Personal Property Tax Audit?​

A business personal property tax audit is a review by a taxing authority to determine whether a business properly reported and valued taxable assets under the applicable jurisdiction’s rules.

Business personal property may include machinery, equipment, furniture, computers, medical equipment and other tangible assets used in business operations. Definitions, exemptions and reporting requirements vary by jurisdiction. Organizations that need broader support with filings, renditions, valuations and portfolio management can learn more about PVS’s business personal property tax services.

During an audit, the taxing authority may compare property tax filings with fixed asset records, depreciation schedules, acquisition and disposal information and other accounting documentation to determine whether the reported property and value are supportable.

The International Association of Assessing Officers (IAAO) notes in its Standard on Valuation of Personal Property that personal property audit programs may include reviewing depreciation schedules, ledger listings and fixed asset records and reconciling those records when they do not balance. IAAO standards are advisory, and applicable state and local laws and procedures govern each audit.

What Happens During a Business Personal Property Tax Audit?​

what happens during a business personal property tax audit

During a business personal property tax audit, the taxing authority typically defines the scope of its review, requests supporting records, compares those records with prior property tax filings and investigates differences involving assets, locations, classifications or values. The process may include follow-up questions before the auditor issues findings or proposed adjustments.

Although procedures vary by jurisdiction, the process commonly includes seven stages.

1. The Business Receives an Audit Notice​

The audit usually begins with written notice or another formal communication identifying what the taxing authority intends to review.

Before producing records, the business should understand the request’s scope.

Review:

  • The legal entity or entities involved
  • Property tax accounts or locations under review
  • Tax years included
  • Response deadlines
  • Requested records
  • The taxing authority’s contact information
  • Any procedural information included with the notice

This is particularly important for multi-location and multi-state organizations. An audit involving one account or facility should be evaluated based on the scope identified by the jurisdiction rather than automatically treated as a portfolio-wide review.

2. The Business Reviews Its Property Tax and Asset Records

The next stage of property tax audit preparation is understanding how prior filings relate to the company’s underlying records.

Businesses may need to compare:

  • Prior BPP returns or renditions
  • Fixed asset ledgers
  • Depreciation schedules
  • General ledger accounts
  • Acquisition information
  • Disposal and retirement records
  • Asset transfer records
  • Lease schedules

The purpose is not simply to gather documents. It is to determine whether the company’s records tell a consistent story.

For example, equipment may have been physically retired but remain on an accounting ledger. An asset may also have moved between facilities while its cost center or accounting location remained unchanged.

Those differences require explanation and documentation, not assumptions.

3. The Auditor Reviews Supporting Documentation​

The auditor may request records that help verify what property existed, where it was located, how it was reported and how the taxable value was determined.

Common records include:

Record

What It May Help Verify

Fixed asset ledger

Assets, costs, acquisition dates and recorded locations

Depreciation schedule

Historical costs and accounting treatment

General ledger

Completeness and reconciliation of asset accounts

Purchase invoices

Asset description and acquisition information

Disposal records

Whether property was sold, retired or scrapped

Transfer records

Movement between facilities or jurisdictions

Lease schedules

Ownership and potential reporting responsibility

Prior BPP filings

What was reported during the periods under review

The exact documentation required depends on the jurisdiction and the issues identified during the audit.

Businesses should understand what each request is intended to verify and organize the response accordingly rather than submitting large volumes of records without context.

4. The Auditor Reconciles Prior Filings With Company Records​

Once supporting records are available, the auditor may compare the company’s property tax filings with its accounting information.

Potential differences may include:

  • Assets in the accounting records that do not appear on the BPP return
  • Property listed in more than one location
  • Disposed assets that remain on a filing
  • Differences between accounting cost and reported cost
  • Equipment transfers not reflected in location-specific filings
  • Significant changes in reported value from one year to another

A difference does not automatically mean the property tax filing was incorrect.

Accounting records and property tax records serve different purposes. A fixed asset ledger may include property that is exempt, located in another jurisdiction, leased or no longer physically present.

The audit response should explain the facts behind the difference and provide documentation where appropriate.

5. The Auditor Reviews Asset Classification and BPP Valuation​

A BPP audit may also examine whether property was classified and valued appropriately.

The review can involve factors such as:

  • Original or historical cost
  • Acquisition year
  • Asset category
  • Physical location
  • Estimated economic life
  • Depreciation treatment
  • Functional characteristics
  • Applicable jurisdictional valuation methodology

Classification matters because different asset types may have different economic lives and valuation characteristics.

For example, high-technology medical equipment, manufacturing machinery, computer servers and office furniture should not automatically be viewed as economically identical simply because each appears on a company’s fixed asset schedule.

Property tax valuation methodology also differs from financial accounting depreciation. Taxing authorities may use cost schedules, depreciation factors and other approaches established by the applicable jurisdiction. Businesses that want additional context on this part of the process can review how assessors evaluate business personal property.

This is why BPP valuation can become a substantive part of an audit rather than a simple review of book depreciation.

6. The Business Responds to Follow-Up Questions

Audits often involve additional questions after the auditor reviews the initial records.

An auditor may ask why:

  • Assets disappeared between reporting periods
  • Costs differ between tax filings and accounting records
  • Reported value changed significantly
  • Equipment moved between locations
  • Certain assets were treated differently from others
  • A particular valuation or classification approach was used

Responses should address the specific question, connect the explanation to available documentation and remain consistent with the business’s broader audit position.

Organized responses are particularly important when several departments are involved. Tax, accounting, finance, operations and asset-management teams may each hold different pieces of the information needed to explain an asset’s history.

7. The Business Reviews the Audit Findings

After completing its review, the taxing authority may issue preliminary or final findings.

The result may involve:

  • No material adjustment
  • Corrections to asset information
  • Classification changes
  • Changes to taxable value
  • Additional assessments
  • Adjustments involving earlier reporting periods

Review the findings carefully against the underlying records and valuation assumptions.

The business should determine whether the proposed changes match the records, whether the valuation assumptions are supportable and whether relevant information was overlooked.

If the business disagrees with the findings, the available next steps depend on the jurisdiction. Those options may include providing additional documentation, requesting a correction or administrative review, discussing disputed items with the taxing authority or pursuing a formal challenge.

PVS’s guide to the business personal property tax protest process explains how a protest may come into play when a business believes an assessment is inaccurate.

What Should a Business Do During a BPP Audit?

A disciplined audit response focuses on accuracy, documentation and consistency.

Confirm the Scope Before Responding

Understand the accounts, locations, periods and records included in the audit before producing information.


Reconcile Records Before Submission

Compare property tax filings with the fixed asset ledger and other supporting records. Identify differences involving acquisitions, disposals, transfers or classifications so they can be explained.


Document Asset Changes

Do not rely solely on an asset’s current accounting status. Where relevant, maintain support showing when property was acquired, relocated, disposed of or removed from service.


Review Valuation Assumptions

Determine whether asset categories, economic lives and other valuation inputs appropriately reflect the property under review.


Track Questions and Responses

Maintain a clear record of requests, documents provided and explanations submitted. This becomes increasingly important during complex or multi-year audits.

The objective is not to produce the largest possible response. It is to provide organized information that supports an accurate property tax position.

Why Are Some BPP Audits More Complex?

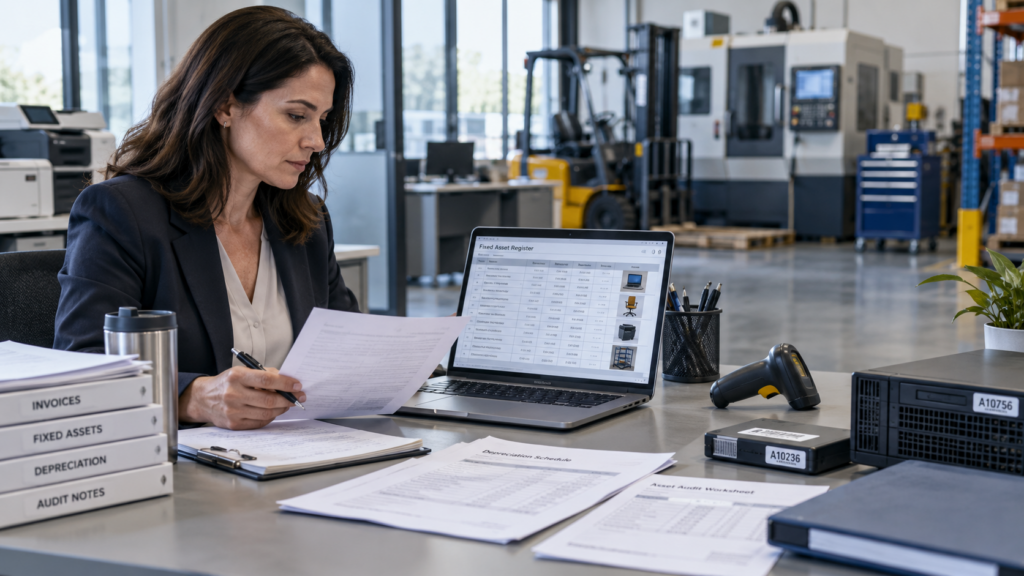
Auditor verifying tagged business assets during a BPP audit

Audit complexity often increases with the size, specialization and geographic distribution of a company’s asset portfolio.

Healthcare

Hospitals, surgery centers, imaging facilities and other healthcare organizations may manage large inventories of specialized medical technology with different acquisition dates, economic lives and replacement cycles.

Rapid technological change can also make valuation analysis more important for certain equipment categories.

Industrial and Manufacturing

Industrial operators may have production machinery, tooling, automated systems, spare equipment and assets that are modified or moved between facilities.

Determining what remained in service, where an asset was located and how equipment should be classified can require input from operations in addition to accounting records.

Multi-Location Organizations

Companies operating across multiple jurisdictions may maintain one centralized asset system while filing numerous local BPP returns.

Asset transfers, acquisitions, closures and accounting-system changes can create differences between the central asset database and location-specific property tax filings.

Because property tax rules vary by jurisdiction, these organizations must also account for different filing requirements, assessment practices and response procedures.

When Can a BPP Audit Require Additional Review?

Some BPP audits require additional review because the records or valuation questions are more complex than a straightforward reconciliation.

Additional review may be useful when:

  • Fixed asset records do not reconcile with prior BPP filings
  • Specialized or high-value equipment requires closer classification or valuation analysis
  • Assets have moved among multiple locations or jurisdictions
  • Acquisition, disposal or retirement records are incomplete
  • Significant differences exist between accounting records and reported property
  • Proposed adjustments depend on assumptions that need to be evaluated against supporting records

In these situations, the focus remains on understanding the records, resolving differences and determining whether the audit findings accurately reflect the property under review.

PVS assists businesses with complex BPP audit reviews involving asset records, valuation questions and supporting documentation. More information is available through PVS’s property tax audit services.

Frequently Asked Questions


How Long Does a Business Personal Property Tax Audit Take?

There is no universal timeline. The duration depends on the jurisdiction, the number of accounts and years under review, the complexity of the asset portfolio, the condition of the records, and the amount of follow-up required.

Businesses should rely on the deadlines and procedural information applicable to the specific audit.

Can a BPP Audit Identify Assessment or Reporting Errors?

Yes, depending on the facts and applicable jurisdictional procedures. Reconciliation may identify retired assets, omitted property, duplicate records, incorrect location information, classification issues or other discrepancies that affect the accuracy of a filing or assessment.

Whether an existing assessment or filing can be corrected depends on local rules, procedures and deadlines.

What Happens if a Business Disagrees With the Audit Findings?

A business may be able to provide additional records, request a correction or review, discuss disputed findings with the taxing authority or pursue a formal property tax protest or appeal.

Available procedures and deadlines vary by jurisdiction, so evaluate findings promptly.

Is Accounting Depreciation the Same as BPP Valuation?

No. Financial accounting depreciation and property tax valuation serve different purposes.

A taxing authority may use cost schedules, depreciation factors or other valuation methodologies established under state or local rules. The appropriate treatment depends on the property and jurisdiction.

How Far Back Can a Business Personal Property Tax Audit Review Records?

No single national lookback period exists. The years subject to review depend on applicable state law, local procedures and the circumstances of the audit.

Businesses should confirm the periods identified in the audit notice and review jurisdiction-specific requirements before deciding which records to produce.

Request a Property Tax Audit Review

A business personal property tax audit requires more than gathering accounting files. Businesses need to understand what was reported, reconcile differences, support asset changes and evaluate whether classification and valuation assumptions accurately reflect the property under review.

PVS helps organizations with complex, multi-location and equipment-heavy portfolios review BPP audit records, valuation questions and supporting documentation.

Request a Property Tax Audit Review

External Source: International Association of Assessing Officers, Standard on Valuation of Personal Property

What Happens During a Business Personal Property Tax Audit? Read More »
Commercial real estate property tax protest experts

Commercial Real Estate Property Tax Protest Success Stories

Dealing with commercial real estate property taxes can be complicated, especially when an assessment does not reflect the property’s current value. A high assessment can raise annual tax liability and create pressure on operating budgets. This is why many property owners review their appeal options before accepting the assessed value.

A property tax protest is a formal challenge to a property’s assessed value as determined by local authorities. The goal is to show that the assessment is too high based on market data, property condition, income, comparable sales or other valuation support. When successful, a protest can reduce property tax liability.

Commercial real estate owners often ask whether property tax protest companies are worth it. The answer depends on the property, the assessment, the evidence and the firm’s ability to support a lower value. The commercial property tax protest success stories below show how PVS has helped clients reduce overassessments across healthcare, retail, office and specialty properties.

Successful Property Tax Protest Examples

Commercial property tax protests are strongest when they rely on clear evidence. That evidence may include market analysis, income data, comparable sales, property condition, functional obsolescence or prior assessment errors. The best outcomes usually come from matching the right valuation argument to the specific property issue.

PVS works with property owners to review assessments, identify overvaluation and support the protest process with documentation. The following examples show how different properties required different strategies. Each case also shows why a one-size-fits-all appeal approach is not enough.

Texas Hospital Valuation Appeal

In 2021, PVS represented a client that owned multiple hospitals in a large Texas jurisdiction. The hospitals were initially assessed at a collective real property value of $314 million annually. This overvaluation created a significant financial burden for the healthcare provider.

PVS prepared an analysis of the taxable value and developed a well-supported position for property tax reduction. The team reviewed the valuation, assessed available evidence and pursued reasonable appeal options. The strategy included direct negotiations with local taxing authorities.

The appeal efforts for the 2020 and 2021 property tax years were successful. PVS reduced the property values to $295 million and $285 million. These adjustments resulted in more than $1.25 million in property tax savings.

Review the full Texas hospital property tax savings case study for more detail on the result.

Missouri Big Box Store Valuation Appeal

PVS represented a Missouri property owner facing an unreasonable valuation increase on a closed and vacant big box store. The local assessor had significantly increased the assessed value of the damaged retail structure and surrounding pavement. The valuation appeared to rely on the lot’s potential use rather than the current property condition.

The property was vacant, vandalized and structurally damaged. There was also no clear market demand to support the inflated valuation. PVS built the appeal around the difference between speculative future use and the property’s real condition.

The appeal led to a 50 percent reduction in assessed value. This created $89,665 in property tax savings for the property owner. The case shows why current property condition can be a critical factor in a commercial property tax protest.

Review the full vacant retail property tax reduction case study for more detail.

hospital property tax protest

A national hospital operator faced a property tax challenge after constructing a new building and vacating most of an older hospital facility. The older hospital became functionally obsolete. However, local assessors continued to assess the property at its previous value.

PVS reviewed the property’s condition and quantified the functional obsolescence of the old facility. This helped challenge the outdated assessment. The appeal focused on showing that the property no longer had the same functional or economic value.

Through negotiation and valuation support, PVS helped secure a major reduction in assessed value. The result was a $23 million reduction for one property tax year. That reduction translated into $690,000 in property tax savings.

Review the full property tax negotiation savings case study for more detail.

Corporate Office Campus In Georgia

PVS challenged an overvalued corporate office campus assessment in Fulton County, Georgia. The property required detailed review because office values can be affected by market conditions, occupancy, comparable sales and income trends. A surface-level assessment may not reflect those changes.

The PVS team prepared a valuation argument using detailed market analysis and comparisons. This helped show that the assessed value was not aligned with the property’s supported value. The appeal focused on objective data rather than a general request for reduction.

The assessment was reduced by $25 million. This resulted in $204,918 in property tax savings. The case shows why office properties should be reviewed carefully when market conditions change.


Review the full corporate office property tax savings case study for more detail.

nursing home property tax protest

PVS handled an appeal for a nursing home in Phoenix, Arizona that was attached to a hospital. After visiting the property and reviewing county records, PVS found that the building had been classified incorrectly. The assessment was also well above market value.

The team filed formal appeals to address the classification issue and reduce the fair market value. PVS also reviewed valuations from prior years to determine whether additional corrections were needed. This helped address both current and past assessment issues.

The appeals resulted in $445,000 in total property tax savings. This included interest and refund checks connected to corrections of prior-year tax rolls. The case shows how classification errors can create significant tax exposure if they are not identified.

Review the full nursing home property tax savings case study for more detail.

For more proof examples, visit the commercial real estate case studies hub.

Property Tax Protest Company Reviews

PVS handled an appeal for a nursing home in Phoenix, Arizona that was attached to a hospital. After visiting the property and reviewing county records, PVS found that the building had been classified incorrectly. The assessment was also well above market value.

The team filed formal appeals to address the classification issue and reduce the fair market value. PVS also reviewed valuations from prior years to determine whether additional corrections were needed. This helped address both current and past assessment issues.

The appeals resulted in $445,000 in total property tax savings. This included interest and refund checks connected to corrections of prior-year tax rolls. The case shows how classification errors can create significant tax exposure if they are not identified.

Review the full nursing home property tax savings case study for more detail.

For more proof examples, visit the commercial real estate case studies hub.

Is it worth it to appeal property taxes?

Yes, appealing property taxes can be worth it when the assessment appears higher than the property’s market value or when the assessor has not accounted for property-specific issues. A successful appeal can reduce the assessed value and lower the tax bill. The savings may continue to matter beyond one tax year.

A commercial property tax appeal is not just about disagreeing with the assessor. It requires evidence. That evidence may include recent sales, income changes, occupancy issues, market studies, property condition, obsolescence or incorrect classification.

Commercial property owners should review appeal opportunities when market conditions shift, income declines, property use changes or the assessment increases sharply. These signals may indicate that the taxable value should be reviewed. Early review also gives the owner more time to gather support before deadlines.

For owners who want to understand the full appeal process, this commercial property tax appeal guide explains how appeals work and what evidence may be needed.

partner with tax professionals

How to win a property tax appeal?

Winning a property tax appeal depends on preparation, evidence and strategy. Property owners need to show why the assessment is unsupported. A clear argument can make the protest process more effective.

PVS reviews each property based on its specific facts. The team looks at valuation, property condition, market data, assessor assumptions and appeal deadlines. This helps determine whether a protest is likely to create value.

Evaluate The Property

The process begins with a detailed evaluation. This may include reviewing market value, location, condition, size, age, income potential and comparable properties. The goal is to identify gaps between the assessed value and the property’s supported value.

A property may be overassessed because the assessor used outdated data. It may also be overassessed because the property has vacancy, physical damage, obsolescence or market challenges. These issues should be documented clearly.

This step helps determine whether an appeal is worth filing. It also helps shape the valuation argument before the protest is submitted.

Collect And Review Evidence

A strong property tax appeal depends on strong evidence. PVS reviews recent sales of similar properties, market studies, income data, property condition and other financial details. Evidence should directly support the requested reduction.

The evidence should show that the assigned value is higher than the property’s true market value or incorrectly reflects the property’s condition. Unsupported claims are usually not enough. Assessors and review boards need documentation they can evaluate.

For Texas property owners, this Texas property tax appeal options guide explains how appeal options and deadlines can affect the process.

File The Appeal

Once the evidence is reviewed, the appeal must be filed before the applicable deadline. Deadlines vary by state and jurisdiction. Missing a deadline can limit the property owner’s options.

PVS can help manage paperwork, submission details and protest deadlines. This can reduce the burden on internal teams. It can also help ensure the appeal is filed with the right supporting information.

In Texas, the standard protest deadline is generally May 15 or 30 days after the assessment notice is mailed, whichever is later. Property owners should confirm the exact requirement with the local appraisal district.

Provide Valuation Reports And Testimony

Some appeals involve informal meetings, local appeal board hearings or more formal proceedings. In these settings, valuation reports and expert testimony can help explain why the assessment should be reduced. The goal is to present a clear, data-supported case.

PVS can provide valuation analysis, market evidence and expert support during negotiations or hearings. This helps assessors and boards understand the reasoning behind the requested value. Clear documentation can also improve settlement discussions.

For complex property types, commercial appraisal and valuation services can support the technical side of the appeal. This is especially useful when the property requires deeper valuation analysis.

Negotiate Strategically

Many property tax appeals are resolved through negotiation. A strong negotiation strategy depends on understanding the property tax code, local assessment practices and the evidence available. The goal is to reach a fair value supported by the facts.

PVS works to identify the strongest position for the property owner. This includes reviewing the assessor’s assumptions, preparing counter-evidence and communicating clearly with local authorities. A professional approach can often lead to settlement before a formal hearing.

Strategic negotiation can save time and reduce uncertainty. It can also help the property owner avoid accepting an unsupported assessment.

Reduce Commercial Real Property Tax Hassle-free with PVS

PVS provides commercial property tax appeal and protest support for accuracy and fairness. The team reviews property valuations to uncover inconsistencies, overassessments and unsupported assumptions. This helps owners determine whether a protest may reduce tax liability.

The PVS team includes experienced property tax professionals and valuation specialists. This combination helps support appeals with stronger data and clearer reasoning. It also helps owners manage the process with less strain on internal teams.

If your commercial property assessment seems too high, PVS can review your appeal options. Contact PVS to discuss your commercial property tax protest with a team that understands valuation, evidence and appeal strategy.


Frequently Asked Questions

What Is a Commercial Property Tax Protest?

A commercial property tax protest is a formal challenge to the assessed value of a commercial property. The goal is to show that the assessment is too high or unsupported so the tax liability can be reduced.

Are Property Tax Protest Companies Worth It?

Property tax protest companies can be worth it when they bring valuation expertise, local assessment knowledge, case evidence and deadline management. They are especially useful for complex commercial properties, multi-state portfolios and high-value assessments.

What Evidence Helps a Commercial Property Tax Appeal?

Helpful evidence may include recent comparable sales, income data, rent rolls, vacancy details, property condition reports, market studies and appraisal analysis. The best evidence directly explains why the assessed value should be lower.

How Long Does a Property Tax Protest Take?

The timeline depends on the jurisdiction, appeal deadline, informal review process and hearing schedule. Some cases may resolve during negotiation, while others may require a formal hearing or additional review.

Can a Commercial Property Tax Protest Lower Future Taxes?

A successful protest can reduce the current assessment and may influence future tax planning. However, future values can still change based on reassessment cycles, market conditions and local rules.

When Should I Contact a Property Tax Protest Firm?

You should contact a property tax protest firm after receiving a high assessment, before appeal deadlines, after major market changes or when property conditions do not match the assessed value. Early review gives the firm more time to prepare evidence.


Commercial Real Estate Property Tax Protest Success Stories Read More »

Texas property tax appeal

Texas Property Tax Appeal Options for Businesses

Business Personal Property Tax

Texas Property Tax Appeal Options for Businesses

Texas property tax appeal options begin with the protest process before an appraisal review board (ARB), followed by additional appeal routes when applicable. Commercial property owners and businesses can challenge an appraisal when they believe their property’s value or assessment is inaccurate.

The process generally begins with a timely protest to the local ARB, followed by an informal conference or formal hearing. If the issue remains unresolved, additional appeal options may be available. Understanding the deadlines, evidence requirements, and differences between the procedures can help businesses determine an appropriate course of action.

These options apply to both commercial real estate and taxable business personal property (BPP), although the documentation needed to support each type of assessment can differ.

What Texas Property Tax Appeal Options Are Available?

Texas provides several ways to challenge a property tax assessment. The appropriate option depends on whether the regular protest deadline has passed, the issue being disputed, and whether the ARB has already issued its decision.

OptionWhen It AppliesWhat It Involves
Informal conferenceAfter filing a protest and before the ARB hearingDiscussing the valuation with the appraisal district to seek a resolution
Formal ARB hearingWhen a timely filed protest is not resolved informallyPresenting evidence to the appraisal review board
Appeal after an ARB decisionWhen the owner disagrees with the ARB’s determinationPursuing eligible judicial or administrative review
Section 25.25 correctionWhen specific appraisal roll errors qualify for correctionRequesting a correction under applicable statutory requirements

An informal conference does not replace the requirement to file a protest on time. Businesses should preserve their formal protest rights while exploring whether the appraisal district can resolve the issue.

When Is the Texas Property Tax Protest Deadline?

Under the general Texas protest rule, property owners must file a notice of protest by May 15 or within 30 days after the applicable notice of appraised value is delivered as provided by law, whichever is later.

For notices sent by first-class mail, Texas law generally presumes delivery when the notice is deposited in the mail. This presumption may be rebutted with evidence of nonreceipt. As a result, businesses should not assume the deadline begins when they physically receive the notice.

Different deadlines or exceptions can apply in specific circumstances. Businesses should review the notice, confirm the applicable filing date with their appraisal district, and avoid assuming that ongoing discussions extend the deadline.

The Texas Comptroller’s appraisal protest and appeal guidance explains the standard filing process, available protest forms, and taxpayer rights.

For companies managing multiple properties, maintaining a calendar of appraisal notices and protest deadlines can help prevent missed opportunities. Each county and property account should be reviewed individually.

business personal property

How Does the Texas Property Tax Protest Process Work?

A Texas property tax protest generally involves reviewing the assessment, filing the notice of protest, evaluating available evidence, and presenting the issue to the appraisal district or ARB.

Step 1: Review the Notice of Appraised Value

Start by examining the appraisal notice and comparing its information with the property’s records.

For commercial real estate, the review may involve the property’s condition, market value, operating income, occupancy, or comparable property data.

For business personal property, the review may focus on asset classifications, equipment values, depreciation assumptions, and the accuracy of reported property.

The objective is to identify a supportable assessment concern rather than assume that every increase is incorrect.

Step 2: File a Notice of Protest

Businesses generally file their protest with the appraisal review board responsible for the property.

The Texas Comptroller provides Form 50-132, Property Owner’s Notice of Protest. A written notice containing the required information may also be sufficient under applicable law.

A protest should identify the property and the issue being challenged. Depending on the circumstances, the concern may involve market value, unequal appraisal, classification, or another qualifying appraisal district action.

Filing on time is important, even when the business expects to resolve the matter through an informal discussion.

Step 3: Request an Informal Conference

An informal conference gives the property owner or authorized representative an opportunity to discuss the assessment with appraisal district staff.

The discussion should focus on evidence relevant to the dispute. For example, a commercial property owner might present current leasing information if the district’s income assumptions do not reflect the property’s market conditions.

If the evidence supports a change, the parties may reach an agreement before the formal hearing.

If the disagreement remains unresolved, the protest can proceed to the ARB.

Step 4: Present Evidence at an ARB Hearing

The ARB provides a formal setting for reviewing the disputed assessment. Both the property owner and the appraisal district have an opportunity to present evidence.

Businesses should organize their records so the board can understand the specific issue and how the supporting information relates to the property’s value.

A clear explanation supported by relevant data is more useful than a general claim that the tax bill is too high.

After reviewing the evidence, the ARB issues its determination for the applicable tax year.

Texas second chance appeal option/Line of business leaders drive tech

What Evidence Can Support a Texas Property Tax Appeal?

The most useful evidence depends on the property type and the basis of the protest. Commercial real estate and business personal property often require different valuation analyses.

Commercial Real Estate Evidence

For income-producing property, relevant documentation may include:

  • Recent sales of comparable properties

  • Rent rolls and lease agreements

  • Operating income and expense statements

  • Occupancy and vacancy information

  • Property condition reports

  • Independent appraisals or market analyses

Market value and unequal appraisal are distinct grounds for protest. A property owner may need to demonstrate that the market value is unsupported, that the property is appraised inconsistently with comparable properties, or both.

Business Personal Property Evidence

For taxable business equipment and other personal property, useful records may include:

  • Fixed asset registers

  • Acquisition costs and purchase dates

  • Equipment descriptions and classifications

  • Depreciation schedules

  • Disposal and retirement records

  • Comparable equipment market data

Businesses with medical equipment, manufacturing machinery, technology assets, or other specialized property may require additional documentation to establish the assets’ appropriate value.

Companies looking for broader reporting and valuation support can review PVS’s business personal property tax services.

Regardless of the property type, evidence should address the specific valuation or appraisal concern being challenged.

Hospital case study

What Happens If You Disagree With an ARB Decision?

An unfavorable ARB determination does not necessarily end the process. Depending on the property’s value, classification, the issue being appealed, and other eligibility requirements, further review may be available.

District Court Appeal

Property owners may appeal an eligible ARB determination to the state district court in the county where the property is located.

A petition for review generally must be filed within 60 days after receiving the ARB’s written order. Judicial appeals involve additional procedural requirements, including applicable tax payment obligations.

Businesses should consult qualified legal counsel before pursuing this option.

Regular Binding Arbitration

Regular binding arbitration (RBA) may be available for qualifying ARB determinations involving appraised or market value or unequal appraisal.

For non-homestead property, eligibility generally depends on an appraised value of $5 million or less, along with the other statutory requirements.

RBA is not available for every type of ARB dispute, so businesses should confirm that the issue being appealed qualifies.

State Office of Administrative Hearings

Property with an ARB-determined appraised or market value of more than $1 million may qualify for an appeal through the State Office of Administrative Hearings (SOAH).

This option applies to qualifying valuation and unequal appraisal disputes involving eligible real or personal property. Industrial property is excluded from this review option.

These procedures have separate deadlines, filing requirements, and costs. Businesses should evaluate their eligibility before selecting an appeal route.

For support with assessment review and protest preparation, PVS also provides property tax protest and appeal services.

What Happens If You Miss the Texas Property Tax Protest Deadline?

Missing the regular deadline can limit a business’s options, but certain exceptions and correction procedures may still apply.

For example, Texas Tax Code Section 25.25 allows specified appraisal roll errors to be corrected under particular conditions. Qualifying circumstances may involve clerical errors, multiple appraisals, or certain substantial valuation errors.

However, a Section 25.25 correction is not a replacement for a regular annual property tax protest. Eligibility depends on the type of error, the applicable tax year, prior protest activity, payment requirements, and statutory deadlines.

Businesses should not assume that a disagreement over value automatically qualifies for a late correction.

For a detailed explanation, review PVS’s Texas Property Tax Code Section 25.25 guide.

How Can Businesses Determine Whether an Appeal Is Worth Pursuing?

An appeal should begin with a review of the assessment and the evidence available to challenge it.

For commercial real estate, an assessment may warrant further examination when the appraisal district’s assumptions do not reflect supported market conditions, comparable property values, or operating performance.

For BPP, a review may identify differences involving asset records, depreciation, classification, or taxable property reporting.

Businesses should also consider the potential financial impact, the cost of gathering evidence, and the time required for the protest or appeal process.

A Texas Commercial Property Example

In a Texas retail shopping center engagement, Property Valuation Services reviewed the income assumptions used in the county’s assessment.

PVS evaluated recently signed leases, asking rents, and comparable properties to determine whether the rental rate reflected available market evidence.

The review resulted in a 20.52% assessment reduction and $26,661 in first-year property tax savings.

The Texas retail shopping center case study illustrates how property-specific income and comparable market evidence can support an assessment challenge.

Results vary according to the property, valuation evidence, and circumstances of the appeal.

When Should a Business Seek Professional Texas Property Tax Support?

Professional review may be useful when a business manages complex properties, substantial equipment portfolios, multiple appraisal districts, or significant assessment changes.

Property Valuation Services (PVS) works with commercial property owners and businesses to evaluate assessed values, examine valuation methodologies, review property records, and identify concerns that may warrant a protest.

A structured assessment review can help determine whether the available evidence supports further action and which appeal option may be appropriate.

Businesses seeking assistance can explore PVS’s Texas property tax valuation services or contact PVS to discuss their property tax assessment.

Understanding the available Texas property tax appeal options is an important first step. Acting within the applicable deadlines and preparing reliable valuation evidence can help businesses pursue an assessment that reflects the property’s supportable value.

Picture of Chip Saam

Chip Saam

Chip Saam, ASA, CMI, spearheads Property Valuation Services (PVS) as Senior Technical Director. With over 25 years of hands-on expertise, Chip specializes in pioneering valuation approaches aimed at maximizing property tax efficiencies and savings for businesses navigating complex property tax landscapes.
Texas property tax appeal

Texas business owners should engage proactively with property tax professionals to ensure unjust tax assessments do not overburden them.

Recent Posts

Texas Property Tax Appeal Options for Businesses Read More »

Business personal property tax appeal

Business Personal Property Tax Appeal Examples

Commercial Real Estate

Business Personal Property Tax Appeal Examples

Successful business personal property tax appeals often begin with identifying errors in asset records, depreciation assumptions, property classifications, or assessment calculations. A well-supported review can reveal whether the assessed value accurately reflects the taxable property and the rules that apply in the jurisdiction.

For companies managing extensive equipment portfolios, these issues can affect multiple locations, tax years, and property accounts.

Property Valuation Services (PVS) has helped businesses address these concerns through assessment reviews, audit responses, informal discussions, and formal appeals. The following client examples show how documented evidence contributed to corrected assessments and property tax savings.

What Can Business Personal Property Tax Appeal Examples Tell Businesses?

Business personal property (BPP) tax disputes do not always involve the same valuation problem. Some result from incorrect asset information, while others require a closer examination of depreciation methods, taxable property classifications, or assessment procedures.

The following PVS engagements illustrate four different situations.

Business / PropertyAssessment IssueDocumented Outcome
Connecticut surgery centerAcquisition-year adjustments during a personal property tax audit$24,000 proposed additional tax liability changed to a $3,000 refund
Texas dialysis clinicAsset deletions and supplies values not reflected correctlyMore than $700 in property tax savings
Missouri regional medical centerHospital building classified on a personal property account$75 million building assessment transferred to the real property parcel
South Texas health care systemEquipment classification and depreciation assumptions$1,000,594 in property tax savings

These cases illustrate different forms of assessment correction. Not every case required the same appeal procedure, and the outcomes should not be interpreted as typical or guaranteed results.

How Did a Connecticut Surgery Center Resolve a Personal Property Tax Audit?

A Connecticut surgery center faced a proposed increase following a three-year personal property tax audit.

During its review of the audit findings, PVS identified an adjustment to the acquisition year of a large group of assets. Because acquisition dates can influence valuation calculations, the proposed changes required a review of the client’s historical asset information.

Assessment Review and Supporting Evidence

PVS examined historical records, researched the applicable state statutes, and organized the findings into a presentation addressing the disputed adjustments.

The team participated in discussions with the assessor and presented supporting information during a hearing before an appeals board.

The objective was to establish whether the auditor’s proposed values were consistent with the documented asset history and applicable requirements.

Documented Result

The proposed $1.1 million increase in assessed value was revised to a $123,000 credit.

As a result, the initial proposed additional tax liability of $24,000 became a $3,000 refund.

This case demonstrates why acquisition records, historical depreciation information, and a documented explanation of valuation differences can be important when responding to an audit.

For a closer look at the assessment issue, evidence, and outcome, read the Connecticut surgery center audit case study.

Businesses facing similar record and assessment questions can review PVS’s property tax audit defense services.

healthcare Business property tax appeal

How Did a Texas Dialysis Clinic Correct Its Business Personal Property Assessment?

A Texas dialysis clinic received a proposed personal property assessment that was approximately 10% higher than its rendered value.

During the review, PVS identified discrepancies between the client’s asset records and the information used in the assessment.

Assessment Review and Identified Errors

The review found that asset deletions had not been reflected in the assessment and that the reported supplies amount had not been updated.

These differences affected the proposed taxable value.

PVS contacted the assessor’s office, explained the discrepancies, and provided the information needed to support a correction.

Documented Result

The assessor’s office corrected the assessment, resulting in more than $700 in property tax savings for the clinic.

Although this case involved a relatively modest dollar amount, it illustrates the importance of reconciling business personal property records before accepting an assessed value.

It also demonstrates that some valuation discrepancies may be resolved through direct communication with the assessor rather than a contested hearing.

How Did a Missouri Medical Center Resolve a Property Classification Dispute?

Property classification can significantly affect how an asset is assessed.

In southeastern Missouri, a regional medical center faced a $75 million assessment on a business personal property parcel for an acute care hospital building.

The building was in the final stages of construction at the end of the preceding year. According to PVS’s case documentation, it was more than 95% complete and had already been partially occupied.

The assessor had classified the building as construction in progress on the tangible personal property account.

Assessment Review and Classification Evidence

PVS reviewed the building’s completion status and the circumstances relevant to its classification as of January 1.

The team appealed the assessment and represented the taxpayer at a hearing, arguing that the building was substantially complete and should therefore be classified as real property rather than personal property.

The distinction mattered because the building had been included in the personal property assessment despite the circumstances supporting its classification as real estate.

Documented Result

The board ruled in favor of the taxpayer.

The $75 million building assessment was removed from the personal property parcel and assigned to the real estate parcel.

The $75 million represents the building’s assessed value, not a $75 million tax refund or savings amount.

This regional medical center case study demonstrates how property classification and supporting documentation can influence the outcome of an assessment dispute.

Preparing documents for appeal

How Did a South Texas Health Care System Achieve More Than $1 Million in Property Tax Savings?

A health care system in South Texas required a detailed review of business personal property assessments involving five hospitals and associated assets.

The case involved specialized medical equipment with different characteristics, useful lives, and potential taxable components.

Equipment Classification and Depreciation Review

PVS reviewed and classified asset listings, comparing the information with its database of high-technology medical equipment.

The review identified components of certain assets that were considered intangible or non-taxable under the applicable treatment. PVS also evaluated depreciation schedules to determine whether assets had been assigned appropriate valuation assumptions.

The team prepared personal property renditions reflecting these findings.

When the appraisal district proposed values that differed from the client’s position, PVS challenged the assessments. The proposed values were appealed and ultimately resolved through mediation.

Documented Result

The review and appeal work resulted in $1,000,594 in property tax savings for the health care system.

The South Texas health care system case study provides an example of how equipment-specific analysis and supporting records can affect taxable personal property values.

The result was specific to the client’s assets, applicable tax treatment, and circumstances.

What Assessment Issues Appeared Across These BPP Appeal Cases?

Although the four engagements involved different properties and jurisdictions, they demonstrate several recurring issues businesses may encounter when reviewing personal property assessments.

Inaccurate Asset Records

Asset additions, transfers, retirements, and disposals may not always be reflected consistently across accounting records, tax filings, and assessment information.

Reconciliation can help identify whether property remains on a taxable schedule after disposal or whether an asset has been reported incorrectly.

Depreciation and Acquisition-Year Differences

Acquisition dates, asset classifications, useful lives, and applicable depreciation schedules can affect taxable value.

The Connecticut surgery center and South Texas health care cases both demonstrate the value of examining the information supporting depreciation-related calculations.

Property Classification Errors

A classification dispute may involve whether an item belongs on a real property account or a personal property account.

The Missouri medical center case illustrates why property characteristics and the applicable valuation date can matter when determining the correct assessment treatment.

Equipment With Specialized Valuation Considerations

Medical equipment and other specialized business assets may contain components that require more detailed analysis.

Where permitted by applicable law, identifying non-taxable components or correcting depreciation assumptions can affect the resulting assessment.

These are potential areas for review, not automatic grounds for an assessment reduction.

property tax appeal specialists

Not necessarily. Some assessment errors can be resolved through discussions with the assessor, while others require a timely formal protest, an administrative hearing, or another statutory procedure.

The appropriate response depends on the jurisdiction, the issue being challenged, and the procedural status of the assessment.

For example, PVS’s Texas dialysis clinic engagement was resolved after the team brought errors to the assessor’s attention. The Connecticut surgery center matter involved audit discussions and an appeals board hearing.

Businesses should not assume that informal discussions extend or replace formal filing deadlines.

Those deadlines vary by jurisdiction. For example, Boulder County’s business personal property appeal guidance describes specific filing periods and subsequent appeal requirements for the county.

For a broader explanation of when and how an assessment may be challenged, read PVS’s business personal property tax protest guide.

Certain jurisdictions also provide limited correction procedures outside the regular protest process. In Texas, Section 25.25 addresses specific appraisal-roll errors subject to statutory conditions. PVS explains those requirements separately in its Texas Tax Code Section 25.25 guide.

When Should a Business Review Its Personal Property Tax Assessment?

An assessment review is particularly useful when a company identifies a significant difference between its property records and the assessor’s information.

Situations that may warrant closer examination include recently disposed equipment that remains on an assessment, asset acquisition dates that do not match supporting records, property classifications that appear inconsistent with an asset’s characteristics, or substantial changes in assessed value without an obvious explanation.

Businesses with multiple facilities or extensive fixed asset portfolios may also benefit from comparing reporting practices across locations.

A practical review should begin with the available documentation, including the asset register, depreciation schedules, assessment notices, prior filings, and records of property acquisitions or disposals.

The next step is to determine whether a discrepancy is material, supported by evidence, and eligible for correction under the applicable jurisdiction’s procedures.

How Can PVS Help Businesses Evaluate BPP Assessment Concerns?

Property Valuation Services works with businesses to review personal property assessments, examine asset classifications, assess valuation assumptions, and identify discrepancies that may warrant further action.

PVS’s business personal property tax services support assessment review, valuation, reporting, compliance, and related property tax concerns.

The case examples above demonstrate how the appropriate response can vary. Some matters require correcting reported data, while others involve a detailed audit response or a formal appeal supported by technical valuation evidence.

For businesses managing specialized equipment, multiple property accounts, or complex assessments, reviewing the available evidence can help establish whether a correction or appeal is justified.

Discuss Your Business Personal Property Assessment

If your business has identified a potential assessment discrepancy, contact PVS to discuss the property, available records, and possible next steps.

The objective is not to challenge every assessment. It is to determine whether the reported property, valuation methodology, and supporting evidence justify further review.

Picture of Chip Saam

Chip Saam

Chip Saam, ASA, CMI, spearheads Property Valuation Services (PVS) as Senior Technical Director. With over 25 years of hands-on expertise, Chip specializes in pioneering valuation approaches aimed at maximizing property tax efficiencies and savings for businesses navigating complex property tax landscapes.
Business personal property tax appeal

"Property Valuation Services has been working for our organization since 2011 performing all property tax compliance, appeal and audit functions. PVS has always performed their work in a trustworthy and professional manner with well-trained staff that communicate effectively, which allows me to focus on other areas of need within the tax department." - Chief Financial Officer, Vibra Healthcare

Recent Posts

Business Personal Property Tax Appeal Examples Read More »

healthcare real estate

Healthcare Real Estate Consulting for Property Tax Management

healthcare real estate

Healthcare real estate consulting plays a key role in managing the financial performance and tax exposure of healthcare facilities. Hospitals, medical office buildings, senior living communities, outpatient clinics and specialty care facilities often face complex property tax issues. These issues can affect cash flow, capital planning, compliance and the ability to reinvest in patient care.

Healthcare property tax management is not just an administrative task. It requires accurate valuation, strong documentation and a clear strategy for reviewing assessments. When a facility is overassessed, the result can be unnecessary tax liability that affects operating budgets.

This guide explains how healthcare real estate consulting can support financial performance through assessment review, valuation strategy, property tax appeals and long-term tax planning. It also shows how healthcare real estate and healthcare personal property tax services often work together for facilities with buildings, equipment and specialized assets.

Understanding the Needs of Healthcare Real Estate in Property Tax Management

Healthcare real estate consulting is important because healthcare facilities are not always valued like standard commercial properties. These properties may include patient care areas, specialized rooms, regulated spaces, medical infrastructure and high-cost improvements. These features can make valuation more complex.

Managing property taxes in this sector affects both financial performance and healthcare operations. A fair assessment can help facilities control costs, preserve capital and support long-term care delivery. An inaccurate assessment can create pressure on budgets and reduce funds that could support operations.

Common challenges include complex valuations, changing market conditions, jurisdiction rules and specialized property use. Healthcare organizations may also need support with lease structures, portfolio planning, facility expansions or property tax appeals. A focused consultant can help connect these issues to a clear tax strategy.

Why Healthcare Real Estate Consulting Matters

Healthcare real estate consultants help facilities understand how assessments are built and where values may be overstated. They can review property records, market data, income trends, occupancy, condition and valuation assumptions. This helps determine whether the current assessment is fair.

Consulting services also help healthcare facilities manage property taxes more efficiently. A structured review can reduce compliance risk, improve documentation and identify savings opportunities. This is especially important for organizations with multiple locations or complex facilities.

A healthcare property tax consultant may also help determine whether a property tax protest is appropriate. If the value appears unsupported, the consultant can help gather evidence, manage deadlines and prepare a stronger appeal strategy.

senior living health care

The Expanding Scope of Healthcare Real Estate

Healthcare real estate continues to evolve as demand grows for hospitals, senior living communities, outpatient centers, medical office buildings and specialized care environments. These property types often have different design needs and operating models. Those differences can affect valuation and assessment review.

Growth in the healthcare real estate market is shaped by aging populations, care delivery changes and technology adoption. As healthcare providers expand or adjust their physical footprint, property tax exposure can become more complex. More properties, more specialized assets and more jurisdictions can create more room for assessment errors.

This makes healthcare real estate consulting more important for organizations that need to manage valuation, compliance and long-term facility planning. A strong consultant can help healthcare owners understand whether property tax assessments reflect the facility’s actual use, condition and market position.

Growing Market Demands

Healthcare facilities often include medical infrastructure, patient care areas, administrative space and unique building systems. These features can affect how a property should be valued. A standard commercial assessment may not fully reflect the facility’s true use, operating limits or condition.

As healthcare portfolios grow, property tax decisions can become harder to manage internally. Organizations may need to review multiple assessment notices, track deadlines and gather property-level evidence across locations. Without a clear process, opportunities to reduce overassessment may be missed.

Consultants who understand healthcare real estate can help facility owners and operators navigate this landscape. They can connect valuation review with appeal timing, budget planning and property tax strategy.

hospital interior

Key Property Tax Management Strategies for Healthcare Real Estate

As healthcare real estate grows, managing property taxes for healthcare facilities becomes more complex. Effective property tax management helps organizations avoid unexpected financial burdens that distract from patient care missions. It also helps leadership understand whether assessed values are supported.

Regular assessment review is important. These reviews should consider the unique value of specialized medical facilities, which may differ from typical commercial properties. The review should also account for current market conditions, occupancy, property condition and facility use.

Healthcare real estate consulting experts can support more favorable property tax treatment by combining property tax knowledge, healthcare property valuation and facility-specific review. They can also help healthcare organizations keep better documentation, prepare for appeals and identify possible savings opportunities.

Review Assessment Notices Early

Healthcare facilities should review assessment notices as soon as they arrive. Waiting too long can create deadline issues and limit appeal options. Early review gives the organization more time to gather evidence.

The review should compare the assessed value with market conditions, income trends, facility use and property condition. If the assessment appears too high, the facility can decide whether a protest or appeal is worth pursuing. This step helps prevent rushed decisions.

Healthcare organizations should also track assessment changes year over year. A sudden increase may be a sign that a deeper valuation review is needed. It may also reveal a classification or data issue.

Document Facility-Specific Factors

Healthcare properties often have special features that affect value. These can include regulated spaces, specialized buildouts, patient care areas, medical infrastructure and equipment-heavy operations. These details should be documented clearly.

A facility may be costly to build but still face valuation issues if parts of the property are obsolete, underused or difficult to repurpose. A standard assessment may not capture those details. Documentation can help show why the assessed value should be reviewed.

Strong documentation may include property records, income data, occupancy details, renovation history, condition reports and market comparisons. The goal is to support a clear and credible valuation position.

Connect Real Estate and BPP Reviews

Healthcare facilities often have both real estate and business personal property concerns. Buildings, land, medical equipment, furniture, technology and specialized assets may all affect total tax exposure. Reviewing only one side can leave savings opportunities untouched.

For facilities with specialized assets, a property tax audit may help identify asset record gaps, valuation issues or documentation concerns. This can support better compliance and reduce future audit risk.

A connected review helps healthcare organizations understand the full property tax picture. It also helps determine whether real estate assessments, personal property filings or both need attention.

What Should Facilities Review Before an Appeal?

Healthcare facilities should review market value, income trends, occupancy, property condition, specialized improvements, equipment, depreciation and local assessment rules before considering a property tax appeal. These factors help determine whether the assessment is supported.

Hospitals, surgery centers, senior living facilities and medical office buildings may have valuation issues that are not obvious in a standard assessment model. For example, a facility may have specialized improvements that are costly to build but do not always translate into market value the same way as traditional commercial property.

A careful review can help determine whether the assessment reflects current use, condition, market demand and income potential. If the value appears unsupported, a healthcare property tax appeal may help correct the assessment.

For a broader explanation of appeal stages, review the personal property and real estate property tax appeals process. This supports healthcare owners who need to understand how the process works before filing.

How To Select a Healthcare Property Tax Consultant

When selecting a healthcare real estate consultant, key factors include healthcare industry experience, property tax knowledge, a record of successful projects and the ability to provide tailored solutions. Healthcare facilities should look for a consultant who understands both valuation and tax strategy.

It is also important to assess communication and client service. Effective communication helps ensure that leadership understands what is being reviewed, why it matters and what action may be needed. A strong consultant should explain valuation issues in a clear way.

Look for consultants who provide updates, respond to questions and understand how property tax decisions affect healthcare operations. A strong consultant should identify savings opportunities, support decisions with credible data and manage the process with organized documentation.

For organizations comparing providers, this guide on evaluating a commercial property tax firm can help clarify what to review before selecting a partner.

healthcare property consulting firm

PVS Healthcare Real Estate Portfolio


PVS has experience reviewing healthcare real estate and property tax strategies for complex facilities. The team evaluates valuation methodologies and how those methods relate to a property’s actual fair market value. This helps healthcare organizations understand whether their assessments are supportable.

PVS is led by a Member of the Appraisal Institute and the American Society of Appraisers. The team includes property tax professionals with backgrounds in appraisal, property tax management, real estate, accounting, economics and finance. This mix helps PVS approach healthcare property tax issues from multiple angles.

As property tax professionals, PVS focuses on practical solutions for healthcare organizations. The team works to identify property tax savings even when a facility has already worked with other consulting or property tax firms.

Healthcare Case Studies

PVS case studies show how focused property tax strategy can support healthcare facilities. These examples include hospitals, assisted living facilities and other healthcare properties with complex valuation concerns. They also show why evidence and facility-specific review matter.

PVS has served more than 800 clients and managed nearly 40,000 property tax parcels across all 50 states. This experience supports healthcare organizations that need national coverage, process control and property tax expertise.

Hospital Operator Savings

Healthcare real estate consulting helped secure significant savings for a national hospital operator. PVS achieved $690,000 in property tax savings through assessment review and strategic negotiations. This reduction helped improve the hospital’s financial position.

Savings like this can free up capital that may support patient care services, staffing, facility upgrades or other operational needs. Property tax savings are not just an accounting benefit. They can affect how healthcare organizations allocate resources.

For a related proof example, review this local hospital property tax savings case study.

Assisted Living Facility Relief

During the COVID-19 pandemic, PVS consulting services helped an assisted living facility struggling with low fill rates. The team supported property tax management strategy that resulted in $1.6 million in savings. This helped reduce financial pressure during a period of lower revenue.

Assisted living properties can face valuation issues when occupancy changes, operating conditions shift or market demand weakens. A standard assessment may not fully reflect those changes. A focused appeal can help correct the taxable value.

For more senior care proof, review the assisted living facility property tax savings case study.

Senior Living Facility Appeal

For a senior living facility in Kansas, PVS filed an appeal that resulted in $40,000 in savings. This result shows how property tax review can benefit smaller healthcare facilities as well as large hospital systems. The value of a review depends on the assessment issue, evidence and local rules.

Savings from a successful appeal can help facilities reinvest in operations, amenities and resident care. Even smaller reductions can matter when budgets are tight. This is why healthcare properties should review assessments regularly.

Decision-Making for Healthcare Property Tax Services

When choosing healthcare real estate property tax consulting, look for advisors who understand healthcare facilities and have experience reducing property taxes through protests, appeals and valuation reviews. A strong provider should understand both the property and the tax process.

Evaluate potential providers by reviewing healthcare experience, success stories, strategy, communication and the ability to manage complex assessment issues. The consultant should be able to explain how they will review the property and what evidence may support a lower value.

Healthcare organizations should also evaluate whether a consultant can support both healthcare real estate property tax consulting and healthcare personal property tax services. Many healthcare facilities have both real estate and business personal property concerns, so the two service areas often need to work together.

PVS Healthcare Real Estate Consultants

PVS offers healthcare property tax services designed for complex facilities and healthcare portfolios. These services can support appeals, valuation reviews, assessment reduction strategy, compliance and professional representation in property tax-related proceedings.

PVS can also support assessment uniformity studies, abatement and exemption research, taxable value reporting and review of all reasonable relief options. These services help healthcare organizations manage property tax exposure with a clearer process.

If your healthcare facility needs support with property tax management, PVS can review your assessment, valuation concerns and appeal options. Contact PVS to discuss your healthcare real estate property tax strategy.

Frequently Asked Questions

What Is Healthcare Real Estate Consulting?

Healthcare real estate consulting helps hospitals, medical office buildings, senior living facilities and other healthcare properties manage real estate decisions, valuation issues and property tax exposure. For property tax purposes, it can include assessment review, appeal support, appraisal analysis and tax savings strategy.

What Types of Healthcare Facilities Benefit From Property Tax Consulting?

Hospitals, medical office buildings, senior living communities, assisted living facilities, rehabilitation centers, surgery centers and outpatient clinics can benefit from tailored property tax strategies. These properties often have specialized layouts, equipment and valuation issues.

Why Is Healthcare Property Valuation Complex?

Healthcare property valuation can be complex because facilities may include specialized layouts, medical infrastructure, regulated spaces, patient care areas and high-cost improvements. These details can affect market value, assessed value and appeal strategy.

Can Healthcare Real Estate Consulting Reduce Property Taxes?

Yes. Healthcare real estate consulting can help reduce property taxes when a valuation review finds that the assessed value is unsupported, too high or based on incomplete property data. Savings depend on the property, jurisdiction and strength of the evidence.

Should Healthcare Facilities Review Real Estate and Personal Property Taxes?

Yes. Healthcare facilities often have both real estate and personal property tax concerns. Buildings, land, medical equipment, furniture, technology and specialized assets may all need review to reduce overassessment risk and improve tax compliance.

When Should a Healthcare Facility Consider an Appeal?

A healthcare facility should consider an appeal when the assessed value appears too high, market conditions have changed, occupancy has declined or the assessment does not reflect the property’s condition. Early review gives the facility more time to gather evidence before deadlines.

Healthcare Real Estate Consulting for Property Tax Management Read More »

commercial property tax firm

Choosing the Right Commercial Real Property Tax Firm

How to Choose a Commercial Property Tax Firm

Choosing the Right Commercial Real Property Tax Firm

Minimizing property tax expenses can protect your bottom line as a commercial real estate owner or business operator. The right commercial property tax firm can help review assessments, identify appeal opportunities and support stronger long-term tax planning. This matters most when your portfolio includes multiple properties, several jurisdictions or complex valuation issues.

Choosing a firm that offers focused commercial property tax services can reduce property tax liabilities and give your team more confidence in the process. A strong firm should understand property valuation, local assessment practices, appeal deadlines and the documentation needed to support a lower value.

This guide explains the main types of commercial property tax firms, what to compare and how to choose a partner for your commercial real estate portfolio. The goal is not to pick the cheapest option. The goal is to choose the firm that can protect your properties, reduce risk and support measurable savings.

accounting firm

Types Of Property Tax Firms

Big Four Accounting Firms

Big Four accounting firms offer broad financial services. Some may provide property tax assistance as part of a wider tax or advisory relationship. This can work well for companies that need many services under one provider.

However, property tax may not be the main focus. Commercial real estate assessments, appeal deadlines and local valuation disputes often require narrow experience. A broad accounting relationship may not always deliver the depth needed for specialized property tax work.

If your company already uses a Big Four firm, it may still make sense to ask how much of the team’s time is focused on commercial property tax. You should also ask whether the people handling your account have direct experience with assessment reviews, appeals and property-specific valuation support.

Local Property Tax Firms

Local property tax firms usually operate within a specific city, county or region. They may understand local assessor practices and common appeal patterns. This can be helpful when a property owner only needs support in one jurisdiction.

The challenge comes when you own properties in multiple counties or states. Managing separate local representatives can become difficult. Each firm may use different reporting processes, timelines and communication standards.

Some local firms also promote their close relationships with assessors. While local knowledge can be useful, property owners should still look for objective analysis, strong documentation and clear appeal strategy. A good commercial property tax firm should protect the client’s interests first.

Law Firms

In some states, legal representation may be required for certain property tax appeals. A law firm with property tax experience can be important when the appeal involves legal filings, litigation or state-specific representation rules. This is especially true when a dispute moves beyond an informal or administrative process.

Not every property tax issue requires legal representation. Many commercial assessment disputes can be handled by experienced property tax consultants, appraisers or representatives, depending on state rules. Texas, for example, has many property tax representatives who are not attorneys.

Before choosing a law firm, review whether legal support is truly required. You should also confirm whether the firm understands valuation, assessment evidence and the commercial real estate market. Legal skill alone may not replace strong property tax valuation support.

National Property Tax Consulting Firms

National property tax consulting firms specialize in property tax matters across multiple jurisdictions. These firms may support owners with broad commercial real estate portfolios, multi-state holdings or complex assets. They often bring process consistency, appeal experience and deeper property tax specialization.

A national firm can also help owners avoid fragmented representation. Instead of managing several local contacts, the property owner can work through one team. This can improve reporting, deadlines, appeal tracking and tax bill review.

Property Valuation Services is a national consulting firm that focuses on property tax and valuation support. PVS provides targeted solutions for commercial real estate owners, including assessment review, appeal support and tax reduction strategies.

What To Compare Before Choosing a Firm

Choosing a commercial property tax firm should involve more than reviewing a contingency fee. A lower fee does not always mean better value. The firm’s experience, reporting process, valuation support and jurisdiction coverage can affect the final result.

Commercial property owners should ask how the firm reviews assessments, how it decides whether to appeal and what evidence it uses. They should also review how often the firm communicates, how it tracks deadlines and whether it reviews tax bills after appeals are complete.

Value Over Contingency Fees

Many property owners compare firms by looking at the contingency fee first. Cost matters, but it should not be the only factor. A low fee does not help if the firm misses appeal opportunities or does not provide enough support.

Value comes from the firm’s ability to identify overassessment, support lower values and protect the owner from unnecessary tax costs. This includes reviewing assessments, monitoring deadlines and checking tax bills for accuracy. A careful review process can matter more than a small difference in fee structure.

With PVS, each property tax bill can be reviewed for accuracy before payment. This helps reduce the risk of overpayment and gives owners clearer information about payment amounts and deadlines. That process supports better financial planning and cash flow management.

Team Qualifications

The qualifications of the team handling your property tax appeals matter. Commercial real estate assessments can involve market data, income analysis, comparable sales, property condition and local assessment practices. The team should understand these factors.

Look for a firm that emphasizes communication and transparency. You should know who is managing your account, how often you will receive updates and what evidence supports an appeal. The process should not feel unclear or reactive.

PVS has a team of commercial property tax professionals with experience in property valuation and assessment review. The firm also provides commercial real estate case studies that show how tax savings were achieved across different property types.

Specialized Valuation Expertise

Commercial property tax work often depends on valuation. A firm with valuation expertise can better assess whether a property is overvalued. This can be especially important when market conditions, occupancy, income or property condition have changed.

A strong property tax firm should know how to review fair market value, compare market data and explain why an assessment may be too high. It should also understand how assessors evaluate properties in different jurisdictions.

PVS provides valuation analysis to support commercial property tax appeals. For owners with more complex valuation needs, commercial appraisal and valuation services can help support assessment disputes with stronger technical review.

Jurisdiction Coverage

Commercial property owners with assets in several locations should ask about jurisdiction coverage. A firm may perform well in one county but lack the structure to manage a larger portfolio. This can create gaps in deadlines, reporting and appeal strategy.

A national or multi-jurisdictional firm can help centralize the process. This is useful for owners with offices, retail properties, warehouses, healthcare properties or other assets across multiple states. Consistency can reduce administrative burden and improve tax planning.

PVS handles property tax work across all 50 states. This allows commercial property owners to use one coordinated team instead of managing multiple local providers. That structure can help improve accountability and reduce missed opportunities.

office building interior

Case Studies Of Commercial Property Tax Savings

Proof should be part of the selection process. A commercial property tax firm should be able to show how it has helped owners reduce assessments or tax liability. Case studies can help you understand the firm’s experience with different property types.

PVS has supported commercial real estate owners across office, retail, healthcare and specialty property types. These examples show how valuation review, market analysis and appeal support can create measurable savings.

Corporate Office Campus

PVS challenged an overvalued corporate office campus assessment in Fulton County, Georgia. The assessment was reduced through detailed market analysis and comparisons. This created significant property tax savings for the owner.

This type of case is important for office owners because office values can shift with occupancy, market rent, operating costs and local demand. A firm should know how to connect property-specific conditions to assessment evidence.

Review the corporate office property tax savings case study for a closer look at this result.

Vacant Retail Property

PVS represented an overvalued closed and vacant big box store. The property’s assessment was reduced by 50 percent, creating meaningful tax savings for the owner. This shows why vacant or underperforming retail properties should be reviewed carefully.

Retail assessments can be sensitive to vacancy, market demand, property condition and comparable sales. A standard assessment may not reflect the challenges of a specific property. A careful appeal can help bring the assessed value closer to the market reality.

Review the vacant retail property tax reduction case study for more detail.

National Hospital Operator

PVS helped a national hospital operator address the overvaluation of an obsolete hospital facility. The case required a detailed review of value, property condition and assessment support. The result was a major reduction in property tax liability.

Healthcare properties can involve specialized real estate, high operating costs and complex valuation concerns. This is why commercial property tax firms should understand the property type, not just the appeal process.

Review the national hospital operator tax savings case study to see how valuation support helped the property owner.

Advantages Of Outsourcing Commercial Property Tax Work

Outsourcing commercial property tax work can give owners access to specialized knowledge without adding more pressure to internal teams. Property tax laws, deadlines and valuation methods can be difficult to manage across multiple locations. A focused firm can reduce that burden.

A commercial property tax firm can manage assessment reviews, appeal strategy, tax bill checks and reporting. This helps internal finance, accounting and real estate teams stay focused on other priorities. It also helps ensure deadlines are not missed.

Outsourcing can also improve valuation accuracy. A firm with market knowledge and property tax experience can identify when an assessment may not reflect current market value. That review can help reduce unnecessary tax costs.

In a changing commercial real estate market, selecting the right property tax firm is even more important. The Tax Policy Center has discussed concerns around office value declines and the impact on city budgets. Market shifts like these can affect assessments, appeals and future property tax strategy.

advantages of outsourcing commercial property tax needs

How PVS Helps Commercial Real Estate Owners

PVS helps commercial real estate owners review assessments, manage appeals and reduce avoidable property tax costs. The team combines property tax process knowledge with valuation support. That combination helps owners challenge unsupported assessments with stronger evidence.

Selecting the right property tax team requires careful review of more than fees. You should consider expertise, communication, jurisdiction coverage, case studies and valuation depth. A firm should be able to explain why an appeal makes sense and how it will support the requested value.

If your commercial real estate assessment seems too high, the next step may be reviewing your appeal options. This commercial property tax appeal guide explains how the appeal process works and what owners should prepare.

For owners ready to evaluate their portfolio, PVS can help review assessments, appeal opportunities and tax reduction strategy. Contact PVS to discuss your commercial property tax needs.

Frequently Asked Questions

What Does a Commercial Property Tax Firm Do?

A commercial property tax firm reviews assessments, monitors deadlines, prepares appeal support, checks tax bills and helps property owners reduce overassessment risk. The firm may also provide valuation analysis and jurisdiction-specific guidance.

How Do I Choose a Commercial Property Tax Firm?

Choose a commercial property tax firm by reviewing its property tax focus, valuation expertise, jurisdiction coverage, case studies, communication process and experience with your property type. Do not compare firms only by contingency fee.

Is a National Property Tax Firm Better Than a Local Firm?

A national property tax firm may be a better fit for owners with properties in multiple jurisdictions. A local firm may work well for one market, but a national firm can provide broader coverage, consistent reporting and portfolio-level strategy.

Can a Commercial Property Tax Firm Help With Appeals?

Yes. A commercial property tax firm can review whether an assessment appears too high, prepare evidence and support the appeal process. The firm may also help with informal meetings, formal hearings and tax bill review.

Why Does Valuation Expertise Matter in Property Tax Appeals?

Valuation expertise matters because commercial property tax appeals often depend on proving that the assessed value does not reflect market value. Appraisal knowledge, market data and property-specific analysis can strengthen the appeal.

When Should I Hire a Commercial Property Tax Firm?

You should consider hiring a commercial property tax firm before appeal deadlines, after receiving a high assessment, when market conditions change or when your portfolio spans multiple jurisdictions. Early review gives the firm more time to identify savings opportunities.

commercial property tax firm

Considerations for choosing the right firm include value over contingency fees; team qualifications; specialized expertise; and jurisdiction coverage.

Recent Posts

Choosing the Right Commercial Real Property Tax Firm Read More »

Property Valuation Services

What Is Property Tax Valuation?

Business Personal Property Tax

What Is Property Tax Valuation?

Property tax valuation plays a crucial role in determining how much tax a property owner will pay each year. For businesses and commercial property investors, an accurate valuation can mean the difference between overpaying taxes and receiving a fair assessment based on true market value.

Whether you’re looking to minimize unnecessary expenses, prepare for an appeal or simply understand the financial standing of your property, knowing how property tax valuation works is essential. This guide will walk you through the fundamentals, common terminology, valuation methods and the step-by-step process to help you navigate property tax assessments with confidence.

For commercial property owners, property tax valuation is also closely tied to commercial real estate property tax consulting, appeal strategy and long-term tax planning. When a valuation does not reflect the actual market value, income potential or condition of the property, businesses may have a stronger reason to review the assessment.

How to Determine the Value of a Property

Several approaches can be utilized to determine a commercial real estate property’s value, including comparable market analysis, income approach to value and the cost approach.

To better understand property valuation, here are some commonly used terms.

Market Value is the estimated worth of a property in the current market. It’s determined by location, property size, condition, amenities, income potential and recent comparable sales.

An appraisal is an expert’s assessment of a property’s value based on location, size, condition and recent comparable sales. Licensed professionals conduct appraisals, which are often required by taxing authorities and the judicial system when appealing a property tax assessment.

Comparative Market Analysis is a method for determining a property’s worth by comparing its value with similar properties in the market. It involves analyzing recent sales data, today’s market trends and property characteristics to assess a property’s value.

Assessed Value is the local government entity’s assigned value to a property. Assessed values are used to determine property taxes and may not always reflect the market value of a property.

Fair Market Value is the price a property would sell for between a willing buyer and seller in an open and fair market. Supply, demand, property condition, location and current market conditions influence fair market value.

Depreciation is the decrease in a property’s value over time due to wear and tear, age or outdated features. It’s an important consideration for property owners because it can affect overall value.

For instance, a property built 20 years ago may have experienced some depreciation due to aging infrastructure, which could lower its value compared to a newer property.

Capitalization Rate estimates a property’s potential income and value based on its expected return. It is commonly used in commercial property valuation to assess investment opportunities.

For example, a commercial property with an expected annual net income of $50,000 and a capitalization rate of 7% would have an estimated value of approximately $714,285.

Highest and Best Use means determining the most profitable use of a property based on market conditions and local zoning regulations. It involves evaluating alternative uses to determine the most financially advantageous option.

A vacant lot in a commercial zone might be more valuable if developed into a retail shopping center than a residential property.

Zoning is the set of local regulations that dictate the approved uses and development guidelines for commercial properties within a designated area. It determines whether a property can be used for residential, commercial, industrial or other purposes.


computing tax

The Property Tax Valuation Process

Step 1: Collection of Data for Initial Assessment 

The first step in property tax valuation involves professional consultants and appraisers gathering relevant information to understand the property’s characteristics, location and prevailing market conditions.

During this phase, they assess the property’s size and condition, considering the number of rooms, amenities and overall appeal. They also analyze the property’s location, including its proximity to schools, amenities, transportation and the neighborhood’s desirability, all of which can impact commercial value.

For business owners and investors, this step matters because incomplete or outdated property data can affect the tax assessed value. If the assessment is based on inaccurate assumptions, the property owner may need a deeper review.

Step 2: Application of Valuation Models/Methods

Property valuers employ various methods to determine the value of a property. The most commonly used approaches include the sales comparison approach, income capitalization approach and cost approach.

Sales Comparison Approach

The sales comparison approach involves comparing the subject property with recently sold properties with similar characteristics in the same area, considering local market conditions as part of the appraisal process.

It’s particularly useful for properties with many comparable sales available. However, finding genuinely comparable properties can be challenging for unique, specialized or income-producing commercial properties.

Income Capitalization Approach

The income capitalization approach, often called the income approach, is primarily used for commercial real estate valuation of investment properties. It values the property’s income potential by analyzing rental income and operating expenses.

This method focuses on the property’s income potential, which is critical for investors evaluating the rate of return on their investments.

However, accurate and reliable rental income data is necessary for an accurate valuation. It may not be suitable for properties that do not generate rental income or where income data is unavailable.

Cost Approach

The cost approach evaluates the value of properties by considering the cost to rebuild or replace them. It is useful for unique or specialized properties where comparable sales or rental income data may be limited or not applicable.

This approach provides an estimate of the property’s value based on the cost of reproducing or replacing it, considering current construction costs and depreciation.

property valuation consultatnts

Step 3: Consideration of Influential Factors

Several factors are taken into consideration when valuing a property.

Location and Accessibility

The property’s location is a key determinant of its value. Proximity to amenities, schools, transportation and the neighborhood’s desirability significantly influence its market value.

Size, Layout and Condition

The property’s physical attributes, including square footage, layout, number of rooms and overall condition, play a crucial role in determining its value. Well-maintained properties generally have higher values.

Market Dynamics and Comparable Sales

The overall real estate market trends, including supply and demand dynamics, along with the recent sales prices of similar properties in the area, are crucial in determining the property’s market value.

This comparison helps assess how the property stands in its current market environment.

Rental Income Potential

Investment properties have significant potential rental income and cash flow. The property’s ability to generate income is a key factor in its valuation, reflecting its profitability and attractiveness to investors.\

Benefits of Property Valuation Services

Property valuation services, led by expert consultants and appraisers, offer numerous advantages regarding commercial real estate property tax assessment. These services are specifically tailored to the unique requirements of commercial properties, ensuring fair and accurate property taxation.

Here are the key benefits.

1. Objective and Unbiased Assessment

These services objectively evaluate the value of a commercial property, ensuring fair property tax assessments that reflect its actual market value.

2. Compliance With Property Tax Regulations and Support for Property Tax Appeals

Experts in property valuation are well-versed in property tax laws, helping to ensure adherence to all relevant guidelines and minimizing the risk of non-compliance and penalties.

Additionally, in the event of a property tax appeal, a professionally conducted valuation report can serve as crucial evidence to support the owner’s case with solid arguments.

3. Identifying Property Tax Savings Opportunities and Mitigating Overpayment

Professionals can pinpoint potential property tax savings specific to commercial real estate, such as eligible deductions and exemptions that can lower the property taxable value, thus reducing property tax liabilities.

Accurate valuations prevent overpaying property taxes, avoid unnecessary financial burdens and enhance operational efficiency.

4. Strategic Financial Planning and Minimizing Assessment Errors

Understanding a property’s value enables owners to make informed financial decisions and optimize property tax-related expenses.

Moreover, expertise in evaluating commercial properties minimizes the risk of assessment errors, providing a reliable valuation that reflects the true market value.

5. Enhanced Negotiation Power

A professionally prepared valuation strengthens your position when negotiating property sales, leases or refinancing because it provides clear and credible evidence of the property’s worth.

6. Improved Investment Decision-Making

For investors, accurate valuations help compare potential purchases, assess portfolio performance and identify properties with the highest return potential.

7. Risk Management and Asset Protection


Knowing the true value of your property helps identify potential risks such as over-leveraging, underinsurance or market volatility, enabling you to take preventive measures to safeguard your assets.

Property Valuation Services experts

Factors to Consider in Choosing the Right Property Tax Service Provider

Experience and Expertise: Property Valuation Services has decades of experience and a solid track record in property valuation. PVS not only holds necessary certifications and accreditations but also provides compelling case studies demonstrating expertise in commercial real estate assessments.

Reputation and Client Feedback: Client feedback and case studies offer insights into reliability and effectiveness in handling complex property tax issues.

Service Offerings, Specialization and Jurisdiction Coverage: PVS is a national consulting firm specializing in the property tax services required for commercial real estate and business personal property. Our comprehensive property tax and building valuation services are tailored to meet the unique demands of commercial properties across jurisdictions.

Efficiency and Cost: We are proud to meet crucial deadlines and offer competitive pricing structures to ensure clients receive timely and cost-effective services. Our ability to efficiently handle property tax needs helps maintain operational continuity and financial stability.

For readers comparing providers, the guide on evaluating a commercial property tax firm can help clarify what to look for before choosing a partner.

Property Valuation Services

Property Valuation Services specializes in assisting commercial real estate owners achieve their property tax-related goals. We focus on providing comprehensive property tax and building valuation services conducted by commercial property tax professionals who consider all relevant factors specific to commercial properties.

With deep market knowledge, we offer valuable insights and customized solutions to effectively address your property tax needs. Our property tax reports adhere to industry standards and guidelines, enhancing credibility with property taxing authorities and regulatory bodies.

PVS values long-term partnerships and prioritizes professionalism. We ensure privacy and data security. You can trust us to uphold confidentiality and integrity throughout the property tax assessment process.

For property owners who need a deeper review, our commercial real estate property tax appeal guide explains how valuation evidence can support an appeal strategy.

Contact us to benefit from expert property tax advice that optimizes your commercial property value and minimizes your property tax liabilities.

Frequently Asked Questions

How often is property tax valuation done?

The frequency depends on local regulations. Some jurisdictions conduct assessments annually, while others may reassess every few years or only when a property changes ownership.

Who performs a property tax valuation?

Licensed appraisers, property tax consultants or government assessors typically conduct property valuations. In some cases, property owners may hire independent valuation experts for appeals or strategic planning.

Can a property valuation help me save on property taxes?

Yes. An accurate and fair valuation can prevent overpayment and identify opportunities for tax savings through deductions, exemptions or corrected assessments.

What is the difference between assessed value and market value?

Assessed value is the value assigned by a local government for property tax purposes. Market value is the estimated amount a property could sell for in the open market. These values are not always the same, which is why property owners may need to review assessments carefully.

Why does property tax valuation matter for commercial real estate?

Property tax valuation matters for commercial real estate because it can affect tax liability, investment performance and appeal opportunities. If the valuation does not reflect income, market conditions or property condition, the owner may pay more than necessary.

Can property tax valuation support an appeal?

Yes. Property tax valuation can support an appeal when it provides evidence that the assessed value is too high or not aligned with market data. A professional valuation can help explain why a correction, reduction or protest may be justified.

What factors affect tax assessed value?

Tax assessed value can be affected by market trends, location, building condition, income potential, comparable sales, depreciation, zoning and local assessment rules. For commercial property, income and market data often play a major role.

Property Valuation Services

Property valuation services, led by expert consultants and appraisers, offer numerous advantages regarding commercial real estate property tax assessment. These services are specifically tailored to the unique requirements of commercial properties, ensuring fair and accurate property taxation.

Recent Posts

What Is Property Tax Valuation? Read More »
Business Personal property Tax Appeal

Understanding Business Personal Property Tax Protests: When and How to Challenge Your Assessment

Business Personal Property Tax Protests

Understanding Business Personal Property Tax Protests: When and How to Challenge Your Assessment

A business personal property tax appeal is a formal process that allows business owners to challenge the assessed value of business personal property for tax purposes. Local government entities determine the value of business personal property within their jurisdiction and calculate taxes based on that assessed value.

However, there may be instances where business owners believe the assessed value is inaccurate, unsupported or unfairly high. When that happens, they may choose to file a formal appeal or protest.

If you have questions about what a business personal property tax appeal includes, when it may be appropriate to file, what steps are involved and how to navigate the process, this guide explains what you need to know.

A property tax protest can help businesses challenge an assessment that does not reflect accurate asset records, depreciation, market value, taxable status or jurisdiction rules. For companies with large asset lists, specialized equipment or multi-location filings, the protest process can be an important part of managing property tax risk.

What is a business personal property tax appeal?

A business personal property tax appeal is a formal procedure through which business owners can dispute the assessed value of their tangible assets for taxation purposes.

Business personal property refers to movable assets used in conducting business, such as furniture, equipment, machinery and inventory. It is distinct from real property or real estate.

Challenging the assessed value of these assets is crucial to ensure a fair and accurate tax assessment. If a business is taxed on a value that is too high, it may pay more property tax than necessary.

Suppose you own a small manufacturing business, and your county assessor determines that the value of your machinery and equipment for tax purposes equals $1,000,000. However, after researching and consulting with industry experts, you believe your assets’ fair market value is closer to $500,000.

This discrepancy could significantly impact your tax bill. By initiating a business personal property tax appeal, you can seek a reassessment that more accurately reflects the true value of your assets, potentially lowering your overall property tax payments.

For businesses that need broader filing, valuation or compliance support, business personal property tax services can help review asset records, depreciation schedules and assessment issues before they become larger tax problems.

While many states assess business personal property tax, New York and Ohio are some of the exceptions, so a protest would not occur in these states. You can check this list from LegalZoom for states that exempt businesses from this property tax.

By presenting evidence such as recent appraisals, sales data for comparable machinery and equipment, depreciation schedules and documentation showing the condition of your assets, you can build a stronger case to support your protest.

The goal is to demonstrate that the assessed value is inaccurately high and does not align with the fair market value of your business personal property.

For real-life inspiration, watch this video to see how a hospital in Texas saved $34K in business personal property tax dollars after filing an appeal.

When should you consider a property tax protest?

Timing is crucial. You typically have 10 to 30 days from the date of the valuation notice to challenge the assessment through a personal property petition.

This process is not applicable in states like New York and Ohio, where local business taxes on personal property are not assessed. You should check local regulations and possibly consult the county board of equalization for specific guidelines applicable to your locale.

Determining whether a business personal property tax protest is appropriate requires careful evaluation. Several scenarios may indicate when it is time to consider filing a protest.

Overvaluation

If you believe the assessor has overvalued your business personal property, resulting in an inflated assessment and higher property taxes than warranted, a protest may be necessary.

For example, if the assessor values your machinery and equipment at $200,000, but recent sales data or industry standards suggest a value closer to $150,000, you can file a protest to seek a more accurate assessment.

Overvaluation can happen when assessors rely on incomplete data, outdated asset records, incorrect classifications or depreciation schedules that do not reflect the real condition or useful life of the assets.

Market Value Changes

Business personal property, such as equipment and machinery, can experience depreciation over time due to technological advancements, wear and tear or changes in market demand.

If your assessment does not consider these factors and reflects an outdated or inflated value, a protest can help adjust it accordingly.

Suppose technological advancements have rendered your equipment less valuable compared to newer models. In that case, you can present evidence of market conditions, expert opinions or depreciation schedules to support your protest.

Demonstrating the depreciation of your business personal property can be a compelling argument for a reassessment that accurately reflects its current market value.

Read this case study to see how a leasing company saved $220K in property tax dollars.

Incorrect Property Information

Errors in the assessor’s records, such as inaccurate descriptions or missing assets, can lead to an incorrect assessment of your business personal property.

A protest can help rectify such errors and support a fair evaluation. For example, if the assessor mistakenly includes assets you no longer possess, this can lead to an artificially higher value.

In that case, you can provide documentation and accurate asset listings to support your protest.

Audit or Record Review Concerns

Businesses should also consider a protest when asset records, depreciation schedules or prior filings raise questions about whether the assessed value is accurate.

A property tax audit can help identify inconsistencies in records, classifications, asset lists or filing details. If the audit shows that reported property values are inaccurate, the business may have stronger grounds to review or challenge the assessment.

What Are the Steps in Filing a Business Personal Property Tax Protest?

While some states like Texas publish a business protest guide for small businesses detailing the steps needed to file an appeal, procedures may vary in other states.

By following the specific guidelines of your local government, you can ensure that you’re challenging your assessment correctly and effectively.

Filing a protest generally involves several crucial steps to challenge your assessment effectively. Following these steps carefully can increase your chances of success.

1. Review the Assessment Notice

Carefully review the assessment notice sent by the county assessor. Note the assessed value, the deadline for filing a petition and any other pertinent details such as the tax rate and any exemption determinations.

This step matters because missed deadlines are one of the most common reasons protests fail. Property owners should confirm the filing deadline, required forms, appeal format and evidence submission rules as soon as the notice arrives.

2. Gather Supporting Evidence

When preparing for a business personal property tax protest, gathering specific supporting evidence for both intangible and tangible personal property is crucial.

Evidence may include depreciation schedules, asset lists, invoices, appraisal reports, photographs, disposal records, comparable sales data and documentation showing how the assets are used.

Incorrect Property Information

Errors in the assessor’s records, such as inaccurate descriptions or missing assets, can lead to an incorrect assessment of your business personal property.

A protest can help rectify such errors and support a fair evaluation. For example, if the assessor mistakenly includes assets you no longer possess, this can lead to an artificially higher value.

In that case, you can provide documentation and accurate asset listings to support your protest.

property tax protest - Property Valuation ServicesWhat are the steps in filing a business personal property tax protest?

While some states like Texas publish a business protest guide for small businesses detailing the steps needed to file an appeal, procedures may vary in other states. By following the specific guidelines of your local government, you can ensure that you’re challenging your assessment correctly and effectively.

Filing a protest generally involves several crucial steps to challenge your assessment effectively. By following these steps carefully and correctly, you can increase your chances of success:

1. Review Assessment Notice

Carefully review the assessment notice sent by the county assessor. Note the assessed value, the deadline for filing a petition and any other pertinent details such as the tax rate and any exemption determinations.

2. Gather Supporting Evidence

When preparing for a business personal property tax protest, gathering specific supporting evidence for both intangible and tangible personal property is crucial. Here are examples of the types of evidence you should consider collecting:

Tangible Business Personal Property

Tangible business personal property is the physical property that can be seen and touched. It includes items such as machinery, equipment, furniture and vehicles.

Recent Appraisals

Hire a licensed professional to independently appraise your tangible business personal property. The appraiser will assess factors like condition, age and market value.

Seek the expertise of professionals who have successfully handled cases and can provide opinions or written statements regarding the accuracy of your property assessment. They can analyze the specifics of your property, review the assessment and provide an expert opinion on whether it is accurate or unjustifiably high.

Their opinions can carry weight during the protest process, so choosing professionals with a proven track record is critical.

Comparable Sales Data

Research recent sales of similar tangible assets in your industry or region. For example, if you own a restaurant and are protesting the assessed value of your commercial kitchen equipment, find comparable sales of similar equipment in your area.

This evidence can demonstrate whether your assets have been assessed higher than comparable assets, strengthening your case during the protest.

Photographs

To support your protest, take clear and detailed photographs of your tangible assets. For instance, if you have outdated machinery that needs repairs, capture those issues in photographs.

These visual records can reinforce your argument and provide tangible evidence during the protest process.

Intangible Assets

Intangible Assets

Intangible assets are non-physical assets that hold value but do not have a physical form. They include intellectual property, software, brand recognition and customer lists.

Expert Opinions

Seek the expertise of professionals specializing in evaluating intangible assets. For example, consult an intellectual property attorney or an experienced appraiser if you have intellectual property.

Their opinions can carry significant weight during the protest process.

Financial Documentation

Gather relevant financial documents that demonstrate the value of your intangible assets. For instance, if you are protesting the assessed value of your brand or customer list, provide financial statements highlighting the income generated by these assets or any licensing or royalty agreements showing their value.

Market Research

Conduct market research to gather data on similar intangible assets in your industry. For example, if you own a software company and are disputing the assessed value of your software code, collect information on comparable software products, sales data and relevant market trends.

This market research can provide valuable evidence to support your case during the protest.

Consider your local property tax authority’s guidelines, as evidence requirements may vary depending on your jurisdiction. Gathering the appropriate evidence and following the correct procedures will help you build a strong case for your business personal property tax appeal.

3. Complete Protest Forms

Obtain the necessary protest forms from your local property tax assessor’s office or website. Complete the forms accurately, providing all required information and supporting documentation.

Make sure the protest form matches the property type and jurisdiction. Some jurisdictions may use different forms for real estate, business personal property or exemption-related disputes.

4. Submit the Protest

Submit your completed protest forms and supporting documentation to the appropriate authority, often the county board of equalization, within the specified deadline.

Follow the submission guidelines provided by your local property tax assessor’s office to ensure your protest is properly filed.

5. Attend a Hearing if Applicable

A formal hearing may be scheduled to review your business personal property tax appeal. If you receive a hearing notice, prepare your arguments, organize your evidence and explain why you believe your property tax should be adjusted.

The hearing is your opportunity to present the facts clearly. A strong argument should connect the evidence to the requested value and explain why the current assessment should be changed.

How Can PVS Help With Your Business Personal Property Tax Appeal?

At Property Valuation Services, we understand the complexities involved in the business personal property tax appeal process, and we’re here to assist you every step of the way.

Our expertise in property valuation can strengthen your case and increase the likelihood of a successful business personal property tax appeal.

Here’s how we can help.

Independent Property Valuation

Our team of experts will conduct an independent evaluation of your business personal property value.

Using in-depth knowledge of local markets and industry-standard valuation techniques, we provide an unbiased assessment that serves as evidence to support your claim.

Detailed Property Reports

We provide comprehensive reports that explain the factors influencing your property’s value. Our analysis includes information on comparable sales, market trends, property conditions and other relevant factors.

These reports can strengthen your case during the property tax protest by providing a clear and thorough explanation of your property’s value.

Expert Testimony

If needed, our team can provide expert testimony during protest hearings.

Drawing on experience and expertise in property valuation, we can present arguments, explain complex valuation concepts and highlight discrepancies in the assessment.

Expert testimony can provide an independent and authoritative perspective that supports a claim for a lower assessed value.

Guidance and Representation

We understand the legal complexities and help ensure you are well-informed. Our team at PVS can handle key parts of the appeal process, from gathering necessary evidence and preparing documentation to navigating challenges.

With strong representation, you can be more confident that your case is being reviewed carefully.

Market Knowledge and Insights

Our team stays up to date with local market trends and changes in regulations. We understand how these factors can impact property values and can provide strategies to pursue during the business personal property tax protest process.

For businesses that need help evaluating appeal strategy, the broader personal property and real estate property tax appeals process guide explains how appeals and protests may vary between property types and jurisdictions.

For companies seeking proof of real outcomes, this BPP return savings case study shows how business personal property tax review can lead to measurable savings.

Contact Property Valuation Services for a fair and accurate assessment of your business personal property value. Our expertise can strengthen your case and reduce the burden of excessive property taxes.

Frequently Asked Questions


What is a business personal property tax protest?

A business personal property tax protest is a formal process used to challenge the assessed value of business assets such as furniture, machinery, equipment, vehicles and inventory. The goal is to show that the assessed value is inaccurate or too high.

When should a business file a BPP tax protest?

A business should consider filing a BPP tax protest when the assessment appears too high, asset records contain errors, depreciation is not properly reflected or disposed assets are still included. Deadlines are often short, so the notice should be reviewed quickly.

What evidence helps support a BPP protest?

Useful evidence can include depreciation schedules, asset lists, invoices, photographs, disposal records, appraisals, comparable sales data and documentation showing asset condition or use. Evidence should directly support the value being requested.

Can a property tax audit support a BPP protest?

Yes. A property tax audit can help identify incorrect asset classifications, outdated records, unsupported values or filing inconsistencies. These findings may help a business decide whether a protest or assessment review is appropriate.

What is the difference between a BPP protest and a property tax appeal?

A BPP protest and a property tax appeal are both processes for challenging an assessment. The terminology depends on the state or jurisdiction. Some use “appeal,” while others use “protest,” but both generally require deadlines, forms and evidence.

Can business personal property tax protests reduce tax liability?

Yes. A successful business personal property tax protest may reduce tax liability if the evidence shows the assessed value is too high. Savings may come from correcting asset records, applying proper depreciation or removing non-taxable items.

Should businesses use property tax protest companies?

Businesses may benefit from property tax protest companies when assessments are complex, asset records are large or jurisdiction rules are difficult to manage. A qualified firm can help review evidence, prepare filings and present valuation arguments.


Business Personal property Tax Appeal

BPPTA is a formal procedure through which business owners can dispute the assessed value of their tangible assets for taxation purposes. Business personal property refers to the movable assets used in conducting business, such as furniture, equipment, machinery and inventory — distinct from real property or real estate. Challenging the assessed value of these assets is crucial to ensure a fair and accurate tax assessment.

Recent Posts

Understanding Business Personal Property Tax Protests: When and How to Challenge Your Assessment Read More »
Business personal property tax

Reasons Your Business Personal Property Taxes Could Increase

Business Personal Property Tax

Reasons Your Business Personal  Property Taxes Could Increase

States that assess property tax on equipment require an annual business personal property return to be filed by a specific date each year.

In most cases, the local assessor’s office reviews the returns filed and performs an analysis to calculate a taxable value for the equipment, including all taxable business personal property — this could include items from aircraft to furniture to machinery and computers.

Some jurisdictions assess the equipment based on how it was filed by the taxpayer without performing any analysis.

This value is most often determined by depreciating the cost of the equipment using either local or state depreciation schedules. As a result, in most cases, newer equipment will yield a higher taxable value initially but will decrease over time as it receives another year’s worth of depreciation until it reaches the residual depreciation factor for the schedule it is being assessed on.

As the assessed value of equipment increases, so does the amount of annual personal property tax. Businesses need to keep good books and records to track all of their equipment, as there can be significant factors in determining business personal property taxes.

Let’s examine the reasons why your business personal property taxes might climb. Understanding these elements can safeguard your business against unforeseen financial strains.

business personal property

Capital Expenditures During the Prior Tax Period

The most common reason for increased business personal property taxes is related to capital expenditures. Personal property taxes would likely increase if there were a large amount of capital expenditures in the prior year.

Common sense tells us that if a company buys a lot of equipment in a prior year, the cost of equipment on the subsequent year’s business personal property tax return will go up and, therefore, so will the value of equipment.

Also, new construction or renovations of your business may require permits to be filed with local authorities.

Based on these permits, an assessor may add value to a personal property account if they believe all or a portion of the cost of the project is related to personal property and is not reflected on the annual business personal property tax return filed.

Assessors’ offices may also conduct field checks of your business annually to ensure that all companies in their respective jurisdictions are accounted for and are reporting an annual return.

In some cases, they may request to tour the site to review the assets being reported on the return compared to what is physically located on site, and they could potentially adjust the valuation they have on the property tax rolls.

Lastly, equipment-related construction in progress may also be taxable as business personal property in some jurisdictions.

audit checklist

Audit Results

The second reason your business property taxes may increase is if your business is selected for an audit. Audits are significant as they can impact not just the current year but preceding years — depending on the state statutes.

Most jurisdictions send out an annual business personal property return form notifying taxpayers they must file. The forms often state the returns are subject to audit, making filing accurately and on time crucial for business personal property tax management.

Some states have very active audit programs (e.g., California, Georgia, Indiana, North Carolina, and Tennessee, to name a few). Many other states are required by statute to perform “desk audits” annually on a certain percentage of accounts from their tax roll.

Consequences of Audit Findings

If your business is selected to be audited, the audit may discover equipment that has either been omitted or erroneously not reported on your submitted annual business listing.

Additionally, equipment picked up in an audit may be penalized depending on the property tax codes for the local taxing jurisdiction.

Certain types of fixed equipment or leasehold improvements are examples of omitted property that may be added to your assessment.

If the improvements are not accounted for in the real estate assessment for the property, the business personal property assessor may add them to the business personal property assessment.

Commonly Overlooked Items

Other types of omitted property may be expensed assets and items the taxpayer felt were nontaxable.

Assets that are expensed and not capitalized on your books and depreciated may be assessable as taxable personal property.

Some states require this figure to be filed and assessed annually, while others may assess multiple years of expensed assets before allowing them to be removed from the return.

Some taxpayers may feel that certain assets are intangible and, therefore not taxable as personal property.

Things like software, freight and installation charges, etc. There are several states that assess and tax these types of assets as personal property.

Inventory and/or Supplies Calculations

Some states assess inventory and/or supplies as business personal property.

Inventory is typically assessed based on the balance on hand as of the lien date while supplies are often valued as a one-month average.

In both cases, the balances are assessed at 100% of their cost. The calculation used to report a supplies balance is a common issue in an audit.

In some states that tax supplies, there is not a consistent formula used across jurisdictions within the state which can lead to confusion for a taxpayer.

Impact of Depreciation Discrepancies

Another reason your taxes can increase in an audit is the reclassification of assets by the auditor. This occurs when the auditor moves assets to a longer-lived, slower depreciating table.

For example, a taxpayer may file certain equipment on a 5-year depreciation table that is moved to a 12-year depreciation table by an auditor.

The slower depreciation rate will cause the value to remain higher over a longer period of time.

Penalties and Interest

Any discovery or increase in value from an audit could be subject to penalty and/or interest.

In some cases, these charges can be extremely punitive.

For example, in North Carolina, audits typically cover the current year plus the prior three years. In this case, penalties can be steep. In the first year, there is a 10% penalty on the additional taxes from the increase in assessment per the audit.

The penalty increases an additional 10% each subsequent year included in the audit, assuming the equipment was owned as of the lien date for that tax year.

That means if the audit covers four years and there is a discovery or increase in the assessment affecting all four years being audited, you would be paying a 40% penalty on the increase in taxes from the audit for the oldest tax year being audited.

Given the complexities of property tax audits, it’s prudent to seek professional assistance from Property Valuation Services (PVS) to ensure accuracy and compliance.

A tax professional can help navigate the audit process, avoid penalties and safeguard your financial interests. Be audit-ready and avoid the consequences.

Examples of leased equipment

Leased Equipment

Another reason for an increase in business property tax is leased equipment.

Capital leases differ from operating leases in that operating leases are typically the responsibility of the lessor to report for business property tax purposes and seek reimbursement for the taxes from the lessee.

However, capital leases can be either the lessor’s or the lessee’s responsibility to report to the local taxing jurisdiction where the equipment is located, depending on the structure of the lease agreement.

property tax appeal specialists

Challenges with Lease Agreements

Sometimes, the lease agreement does not clearly state who is responsible for reporting the equipment.

Equipment can potentially be double-reported by both the lessor and the lessee.

In these cases, businesses need to understand the implications and properly report, or not report the leased equipment to avoid potential issues with duplicate taxation.

At times, this can be extremely challenging to correct as the cost and description of the equipment can differ between the lease contract and how the equipment is ultimately booked to the lessee’s fixed assets.

Additionally, we’ve seen instances where operating leases end and the lessor files a final return for the equipment stating that the lessee retained the equipment when the lease ended.

The assessor then adds value for the leased equipment to the lessee’s personal property assessment. However, it was later discovered that the equipment was returned to the lessor when the lease ended.

Lastly, state statutes differ as to who is responsible for reporting leased equipment, regardless of the verbiage in the lease agreement.

depreciation table

Depreciation Tables

The depreciation tables used by your local jurisdiction for business personal property purposes could also increase your property taxes.

What is Depreciation?

Depreciation can be simply defined as an asset’s loss in value caused by physical deterioration, functional obsolescence, or external obsolescence. It’s important to note that accounting depreciation, income tax depreciation, and property tax depreciation are most often different from each other.

Local Taxing Jurisdictions and Depreciation Adjustments

The depreciation tables used by assessing jurisdictions across the country vary widely in length and speed of depreciation.

For example, most assessors will value technology-heavy equipment and computer equipment on a 3-year or 5-year table while valuing furniture and fixtures on a 10-year or 12-year table.

Some assessors within a state may all use the same set of depreciation tables while in other states, each local jurisdiction may have its own unique set of tables.

In Indiana, the percent good factor for the most commonly used table increases from the first year to the second year on new equipment purchases, so the taxable value of the equipment increases in the second year it’s owned before beginning to decline.

It’s interesting to note that the third-year factor is also still higher than the first-year factor.

For personal property tax purposes in most taxing jurisdictions and most depreciation schedules, the taxable value of the equipment does not depreciate down to zero.

The remaining depreciation percentage at the bottom of each depreciation table is called a residual factor.

As long as the business owns an asset, it will be valued at the residual factor until the equipment is no longer at the facility.

How low the factor goes depends on the useful life of the asset, but an increase in any of these factors can lead to significant business personal property tax increases if your business has a lot of older equipment.

We have seen some local taxing jurisdictions increase the residual depreciation factors for the schedules they use to value the equipment and thereby materially increase the assessed value of the equipment.

Abatement or Exemption Expiration

You might see an increase in your property tax liability from the prior year if an exemption or abatement agreement related to property taxes expires.

Some jurisdictions will grant businesses a full or partial abatement of property taxes for a certain number of years to promote the development of an area.

For example, in Nevada, there is a 10-year and a 20-year partial property tax abatement for data centers if they meet specific state requirements, including investing a certain amount of capital assets in the county where the data center resides and requiring a certain percentage of employees engaged in the construction of the data center be residents of Nevada.

In some instances, a business may be able to negotiate favorable property tax treatment for a period, which is typically also tied to an agreed-to capital investment during the period of the preferential tax treatment.

When these exemptions end or begin to be phased out, it can lead to a substantial increase in property tax liability that must be considered for budgeting purposes.

Tax rate increase

Tax Rate Increase

One unforeseen reason property taxes can increase is due to property tax rate increases adopted by local jurisdictions.

Most of the property tax revenue collected by local jurisdictions goes towards various government departments and projects within their jurisdiction (like upgrades to existing roads or schools within the jurisdiction).

Therefore, local taxing jurisdictions may increase property tax rates to fund these projects.

Some jurisdictions list the budgeted property tax rate on the assessment notice if certain propositions are approved locally.

Sometimes, these property tax rate increases can be substantial. In 2020, the property tax rate in Nashville, Tennessee increased 33% from the prior year.

Assessor Errors

Lastly, property taxes could increase due to an error in calculating the business personal property tax return.

Assessors in bigger taxing jurisdictions process a large number of personal property tax returns, sometimes in a short period of time, and mistakes can be made.

We’ve seen instances where an assessor’s office does not remove a deletion if it’s a larger piece of equipment that seems integral to business operations and nothing appears to have replaced the equipment.

Or they may ask for a disposal date before removing the equipment. Other times, the deletions can just get overlooked by the assessor, and in these cases, taxpayers have the right to file an amended return and request a refund for any overpaid property taxes.

Additionally, there can be clerical errors. If the assessor accidentally enters another digit when entering the costs reported by the taxpayer, it could significantly increase the property tax burden for that year.

If these types of errors are found before the deadline to appeal the account, they typically can be corrected informally after discussions with the assessor if any additional documentation requested is provided.

However, if you miss the appeal deadline date, you may be unable to appeal and correct these errors, resulting in a higher property tax bill.

Let Property Valuation Services (PVS) Assist with Personal Property Tax Renditions

Personal property taxes can be daunting. According to the Tax Foundation, “Complying with personal property taxes is onerous, as it requires documenting all assets—all the way down to cleaning supplies for the office kitchen—along with their acquisition price, acquisition date and depreciation.”

Given these challenges — not to mention the ever-changing landscape of property taxes — it’s wise to consider professional help.

PVS’ business property tax professionals can simplify the process of preparing personal property tax renditions and aid in budgeting expected taxes.

Contact us today to ensure that your business plans effectively and meets tax obligations without delays.

Frequently Asked Questions

How can my business prepare for a potential property tax audit before it happens?

Businesses can prepare by maintaining detailed asset records, reconciling equipment lists regularly, keeping copies of all capital expenditure documentation, and reviewing prior filings for consistency.

How often should I review my jurisdiction’s depreciation tables and tax rate changes?

You should review them annually — ideally before filing returns — because changes to depreciation schedules or residual factors can directly affect taxable values.

What should I do if both my business and a leasing company report the same equipment?

You should immediately contact the assessor to provide proof of the correct ownership and reporting responsibility, supported by your lease agreement and any return documentation, to prevent double taxation.

Business personal property tax

As the assessed value of equipment increases, so does the amount of annual personal property tax. Businesses need to keep good books and records to track all of their equipment, as there can be significant factors in determining business personal property taxes.

Recent Posts

Reasons Your Business Personal Property Taxes Could Increase Read More »
duplicate taxation

Real vs. Personal Property Tax: The Fight Against Duplicate Taxation

Business Personal Property Tax

Real vs. Personal Property Tax: The Fight Against Duplicate Taxation

When companies consider property taxes, the focus is often on real estate property tax. However, it’s equally crucial to understand the distinction between real property, which includes the land and any permanent structures, and business personal property, which are movable items like equipment and furniture. This differentiation influences financial reporting, property tax liability and compliance with varying state laws.

Accurate property evaluation and building valuation services ensure that both real and personal property are assessed fairly. Misunderstanding these nuances can lead to misclassifying assets, which might result in overpaying property taxes or penalties for non-compliance. Accurate classification aids in strategic financial planning and efficient asset management, helping companies avoid legal issues and optimize their property tax strategies, ultimately safeguarding their profitability and reputation. 

What is Personal Property?

Business personal property (BPP) includes items not permanently attached to the land, such as equipment and furniture. The critical difference lies in mobility—personal property can be moved, while real property is fixed and immovable.

While not as familiar to most business operators, BPP tax is assessed and collected on the equipment, furniture, and fixtures inside a building or other movable items such as RVs, boats, vehicles, and machinery.

Real estate is typically considered fixed or permanent; BPP is considered “movable” and tangible—items that would be taken if a business vacates its building.

Examples include computer and IT equipment, manufacturing equipment, interior signage, furniture, and more. Depending on the state, it may also include interior building changes made by the tenant, referred to as leasehold or tenant improvements, which are the most common assets facing duplicate property taxation.

Business owners must report their BPP on their tax return, including the total cost of the assets, income tax depreciation, and net depreciated value.” with “cost and year acquired of each asset.

What is Real Property?

Real property refers to land and structures on it. This includes houses, buildings, and improvements like paving and lights. Payment for commercial real estate property tax can vary. These property taxes are sometimes paid through an escrow account, similar to a residential mortgage. In other instances, tenants pay the property tax to landlords as part of their rent. Property owners might also pay the local property tax collector directly.

Real property tax may be more familiar because it’s a significant expense; depending on the building type, size, and location, it might be the most substantial cost for tenants or building owners. But it isn’t the only type of property tax in most states.


How is business personal property different from real property?

Business personal property (BPP) includes items not permanently attached to the land, such as equipment and furniture. Real property refers to land and structures on it. The critical difference lies in mobility; personal property can be moved, while real property is fixed and immovable.

Real property is land and anything built on it. This includes houses, buildings and improvements like paving and lights. Payment for commercial real estate property tax can vary. These property taxes are sometimes paid through an escrow account, similar to a residential mortgage. In other instances, tenants pay the property tax to landlords as part of their rent. Property owners might also pay the local property tax collector directly.

Real property tax may be more familiar because it’s a significant expense; depending on the building type, size and location, it might be the most substantial cost for tenants or building owners. But it isn’t the only type of property tax in most states. 

While not as familiar to most business operators,  BPP tax is assessed and collected on the equipment, furniture and fixtures inside a building or other movable items such as RVs, boats, vehicles and machinery.

Real estate is typically considered fixed or permanent; BPP is considered “moveable” and tangible — items that would be taken if a business vacates its building. 

business personal property

Overview of Business Personal Property Valuation

Personal property assessments for businesses are primarily derived from the company’s fixed asset listing, which may also encompass inventory, supplies and leased equipment, contingent on the state’s regulations. 

Companies must submit a BPP rendition annually to the relevant property taxing authority detailing all business-owned assets as of the lien date. This submission should include acquisition dates and costs of all taxable personal property.

State-Specific Property Taxation and Deadlines

Thirty-eight states in the United States impose taxes on business personal property, with most adopting Jan. 1 as the lien or valuation date. Each state stipulates its deadlines for filing personal property returns, typically from Jan. 31 to May 15, although some states set later deadlines. Businesses must be aware of their specific state deadlines to ensure timely compliance.

Asset Types and Property Tax Application

Depending on the state, personal property taxes may apply selectively to certain asset types, such as aircraft, business machinery and computers or more broadly to all personal property categories. Businesses must familiarize themselves with the local laws and regulations to file their returns correctly and avoid potential issues with duplicate taxation.

Calculation of Property Taxable Value

Property tax assessors determine the value of each asset by subtracting depreciation from the acquisition cost. Depreciation rates vary significantly and are influenced by the asset’s type and age. Typically, assets are grouped into categories such as office furniture, manufacturing equipment, medical devices and communication technology. Most property tax assessors apply a specific depreciation schedule for each category, which differs from book or federal depreciation methods. However, some states use federal property tax classifications to determine appropriate asset depreciation.

Navigating the complexities of BPP taxation requires deep expertise, particularly in understanding varied state laws and accurately calculating asset depreciation. Property Valuation Services (PVS) offers specialized valuation services that help businesses meet their property tax obligations and avoid overpayments and penalties by ensuring accurate asset assessments and timely compliance.

Overview of Commercial Real Property Valuation

Like the valuation of business personal property, commercial real estate (CRE) is determined as of a lien date, typically set on Jan. 1. Unlike personal property, the valuation process for real estate usually doesn’t start with submitting an annual return.

State Requirements and Assessment Initiation

In several states, commercial property owners must report any changes in building structure, new constructions and occasionally income and expense details to their local assessors annually. However, most states do not mandate filings related to the building or land itself. Instead, local property tax assessors independently initiate accurate property valuation and notify owners of the assessed values.

Assessment Procedures and Frequency

The valuation process may include a physical inspection of the property or a desk review by the assessor. The frequency of reassessments varies by state; for example, Texas, Kansas and Georgia conduct annual real property reviews. In contrast, Iowa and Missouri reassess real estate every odd-numbered year, while Tennessee and North Carolina follow a statutory schedule, reassessing property every four to eight years.

Appeals and Review Process

Upon receiving a valuation notice, property owners have a designated period to contest the assessor’s market value estimation. To argue for a lower assessment, taxpayers must provide supporting data such as income statements, leases or market comparisons. 

The appeal process typically involves formal procedures, including discussions with appraisal staff or hearings before a board composed of local citizens, commissioners or appraisers. 

Here is a comprehensive guide to commercial real estate property tax appeals.

commercial real estate property

Duplicate Taxation: When Real Property Becomes Business Personal Property

According to most state statutes and laws, the real estate assessment is an estimate of the fair market value of the building and improvements as of the lien date, meaning the anticipated price at which it would sell in an arms-length transaction between a willing buyer and seller.

Logic asserts that the sale of a building would include the exterior walls and everything inside, in addition to the land and land improvements. This seems like a simple concept, but many states across the country complicate the matter, arguing that various real estate components are business personal property, such as leasehold improvements or tenant buildout. If the property tax assessor is taxing real property at its reasonable selling price and taxing building components on the personal property account, that’s double taxation — and illegal.

Terminology and Building Components

Knowing the components of a building and industry terminology is important when discussing the double taxation of property on the real and personal sides. 

The term “shell” is a building composed of four walls, a floor and a roof. It has exterior walls and windows installed, as well as concrete or other base floors, but does not contain interior dividing walls, like exam rooms in a medical office building (MOB) or cubicles in an office. 

It does not include other finishes like tile, carpet, acoustic drop ceilings, interior lighting, paint, wallpaper or common area décor. Those are often called “tenant improvements” or “leasehold improvements” — interior buildouts inside the four walls of a building.

It’s common for the developer or owner of the real property to construct or build both simultaneously – a fully functioning building from the start. But it’s also common for a real property owner to construct and own only the shell building and for tenants to build or install their interior buildout, specific to their liking, use or industry. This happens frequently in special-use properties, like those in the medical community or buildings with a high turnover rate and generic use space, like retail or office buildings.

Challenges of Duplicate Taxation

Regardless of ownership, most buildings are fully complete — meaning they contain shell and tenant improvements — and are fully functioning real estate. However, those who own or install each component can lead property tax assessors in various jurisdictions nationwide to tax them separately and often twice.

Duplicate taxation also commonly occurs when business owners list real-estate-related assets from a fixed-equipment or leasehold improvement account on their property tax return. In-house accounting staff and CPA firms make this common mistake, listing items from fixed-equipment or leasehold accounts as tangible or movable assets. 

Property tax assessors are most likely to accept a return as it is filed rather than question the taxpayer on these assets when reviewing such renditions. After all, it’s additional revenue for their county and city.

Connecticut’s Approach to Duplicate Taxation

Connecticut is a great example of the struggle with duplicate taxation on tenant improvements. Many state property tax assessment offices use a third-party appraisal firm to analyze and set the town’s real estate values.

In PVS’s experience, these real estate assessments are typically at market value for a fully built-out building. That means the valuation estimates what that building would sell for with shell and tenant improvements exactly as it stands as of the lien date.

The assessment office or their third-party firm reviewed local market sales of similar properties, current lease rates and listed market rents to estimate what the building would generate in revenue for a potential buyer. This real estate assessment, therefore, includes the entire building as it stands, including tenant improvements.

At the same time, Connecticut assessors, who typically handle the valuation of business personal property in-house, will value interior buildout completed by tenants in a building on their business personal property account. This is largely because the tenant paid for and installed those walls, flooring, etc., so they appear on the tenant’s fixed asset listing or general ledger. They will assert that any physical additions or changes inside the building, not installed or owned by the actual property owner but rather the tenant, are taxable as tenant improvements.

Avoid or Resolve Duplicate Taxation with PVS

The fight to eliminate this double property taxation can be challenging, which is why owners/landlords and tenants approach commercial property tax firms like Property Valuation Services (PVS). The process involves proving that the real estate assessment reflects the total market value, requiring building valuation services that offer expert appraisals, industry knowledge, access to market data and comprehensive valuation experience.

The process requires proving that the real estate assessment is at total market value, which involves valuation services that offer appraisal and industry knowledge, access to market data and extensive valuation experience.

Knowing also which personal property assets, like specific fixed equipment, should be taxed as personal property is critical to determining their assessed value. The resolution typically requires a formal appeal on the business personal property account, so the taxpayer must possess knowledge of both forms of property tax.

Leverage PVS’s Expertise for Effective Business Personal Property Tax Solutions

PVS knows how to accurately prepare and file the annual business personal property rendition, which can provide a large head start on duplicate taxation issues. Having a business personal property tax professional prepare the personal property return on time can also avoid costly and time-consuming audits, which can often review up to four prior years of personal property data. 

Hiring a firm with expertise and experience in real and personal property is invaluable when duplicate taxation issues plague your property tax expense.

Attention to detail, industry knowledge and experience and knowledge of legislative changes are essential in the skill set of the company filing your business personal property returns. PVS specializes in business personal property taxes and has prepared returns and challenging property tax assessments since 1997. 

Contact us to see how we can help you and your company file your renditions and avoid or resolve duplicate taxation from local governments.

Frequently Asked Questions

Why is it important to distinguish between real and personal property for tax purposes?

The classification affects how assets are assessed and taxed. Misclassification can lead to overpayment, tax penalties, or duplicate taxation.

How is real property taxed?

Real property is taxed based on its assessed value, which includes land and any permanent structures. Taxes are typically paid annually to the local tax authority.

How can a business ensure accurate classification of property?

Work with professional property evaluators or tax consultants who understand local laws. Regular asset reviews and audits can also help ensure accuracy.

 
duplicate taxation

Accurate property evaluation and building valuation services ensure that both real and personal property are assessed fairly. Misunderstanding these nuances can lead to misclassifying assets, which might result in overpaying property taxes or penalties for non-compliance. Accurate classification aids in strategic financial planning and efficient asset management, helping companies avoid legal issues and optimize their property tax strategies, ultimately safeguarding their profitability and reputation.

Recent Posts

Real vs. Personal Property Tax: The Fight Against Duplicate Taxation Read More »